
Blogs
PW Consulting: Global Boat Black Water Treatment Market to Hit $854.13M by 2032 at 6.89% CAGR
By pmarketresearch, 2026-09-16
Navigating the Currents: Strategic Intelligence for the Worldwide Black Water Treatment System for Boats Market (2026-2032)
Executive Overview: The Imperative for Precision Intelligence
As the maritime industry accelerates toward stricter environmental compliance and operational sustainability, the management of vessel-generated black water has evolved from a regulatory checkbox into a core component of marine engineering strategy. PW Consulting is pleased to introduce our comprehensive Worldwide Black Water Treatment System for Boats Market research, a strategic intelligence asset designed to equip decision-makers with the clarity required to navigate a sector defined by evolving regulatory frameworks, technological diversification, and shifting demand patterns across leisure, commercial, and defense segments.
This market study is built on a rigorous analytical foundation spanning historical performance from 2020 through the base year of 2025, with a forward-looking forecast period extending to 2032. Drawing from primary research, expert interviews, and verified secondary datasets, the report provides a 360-degree view of market structure, competitive positioning, and growth vectors. For executives evaluating capital allocation, product development roadmaps, or market entry strategies in the marine sanitation space, this intelligence serves as a critical reference point for minimizing risk and identifying high-value opportunities.
The maritime environment is no longer operating in a static regulatory landscape. Compliance with MARPOL Annex IV, IMO MEPC.227(64) effluent standards, and USCG classification requirements has fundamentally reshaped procurement cycles, technology selection, and vessel retrofit strategies. In this context, general industry narratives are insufficient. Stakeholders require granular, verified, and actionable intelligence that connects regulatory traction to commercial viability. Our report delivers precisely that: a consolidated, data-backed perspective that transforms market complexity into strategic clarity.
Market Trajectory and Growth Vector: A Data-Backed Lens
The worldwide market for black water treatment systems for boats has demonstrated consistent expansion over the past half-decade, reflecting a confluence of vessel modernization, environmental enforcement, and the growing commercialization of marine leisure and offshore operations. Based on verified revenue tracking, the market reached a valuation of approximately 535.4 million USD in the 2025 base year, following a measured growth curve from 382.45 million USD in 2020. This progression underscores a sector that has moved beyond early adoption dynamics into a phase of structured, demand-driven expansion.
Looking ahead, the forecast period through 2032 indicates sustained upward momentum, with a projected compound annual growth rate of 6.89 percent. By 2032, the market is anticipated to reach an estimated 854.13 million USD, signaling a meaningful expansion in total addressable demand. This trajectory is not merely a function of broader marine industry growth; it is increasingly tethered to regulatory-driven retrofitting, the replacement of legacy holding-tank-dependent configurations with advanced treatment technologies, and the integration of wastewater management into broader vessel system architectures.
Importantly, this growth is not uniform across all vessel classes or geographic deployments. The market's expansion is being shaped by differentiated adoption curves, varying compliance stringency, and distinct procurement behaviors between recreational, commercial, and defense end-users. Understanding where value is concentrating, which technology pathways are gaining traction, and how regional regulatory environments influence purchasing decisions is essential for any organization seeking to capture share in this evolving landscape. Our report unpacks these dynamics with precision, enabling clients to move beyond top-line growth narratives and develop segment-specific strategies grounded in verified market structure.
Segmentation Landscape: Technology, End-Use, and Regional Configuration
The architecture of the black water treatment system market is defined by three critical segmentation dimensions: system type, end-use application, and regional deployment. Each dimension carries distinct implications for product specification, certification pathways, pricing dynamics, and competitive positioning.
At the technology level, the market is structured around multiple marine sanitation device classifications and treatment methodologies, ranging from electrochemical and heat-based systems to biological and membrane-assisted platforms. These technology pathways are not interchangeable; they are governed by vessel size constraints, discharge zone regulations, operational profiles, and maintenance expectations. Type II and Type III marine sanitation devices have emerged as significant components of the market structure, reflecting their broader applicability across inspected vessels, larger recreational craft, and commercial platforms. Meanwhile, specialized Type I configurations continue to serve a focused but strategically important segment of smaller vessels operating under specific discharge allowances. The interplay between certification requirements, system complexity, and total cost of ownership creates a segmentation environment where technology selection is as much a compliance and operational decision as it is a product choice.
End-use segmentation further differentiates demand behavior. Leisure boats and yachts represent a substantial portion of market activity, driven by owner expectations for compact, odor-free, and low-maintenance solutions, as well as increasing environmental awareness within the recreational marine sector. Commercial vessels constitute another major demand pillar, where treatment system selection is shaped by operational uptime requirements, crew size, voyage duration, and compliance obligations across multiple jurisdictions. Military and defense applications, while smaller in relative scale, introduce distinct procurement dynamics tied to standardization, durability, and mission-specific performance criteria.
Regionally, the market reflects a concentration of activity in established maritime economies, while emerging marine markets present incremental but structurally important growth potential. Regulatory maturity, vessel fleet composition, after-sales service infrastructure, and local certification pathways all influence how regional demand translates into commercial opportunity. Rather than presenting isolated regional snapshots, the report integrates these geographic dynamics into a cohesive global map, helping clients identify where market presence is strongest, where compliance-driven demand is accelerating, and where tactical entry or expansion strategies may yield the highest return.
Regulatory and Operational Dynamics Shaping Market Behavior
The commercial trajectory of marine black water treatment systems is inextricably linked to the regulatory environment. International and national standards do not simply define compliance boundaries; they actively shape technology adoption, vessel design priorities, and procurement timelines. Under MARPOL Annex IV, vessels of 400 gross tonnage and above, or those certified to carry 15 or more persons, must be equipped with an approved sewage treatment plant, a sewage comminuting and disinfecting system with holding tank, or an appropriate holding tank configuration. Discharge of untreated sewage is restricted to distances beyond 12 nautical miles from the nearest land, at approved rates while underway at not less than 4 knots. These parameters create a baseline compliance framework that directly influences equipment specification across commercial and larger recreational vessels.
Ballast Water Treatment Equipment Market
Further refining the compliance landscape, IMO Resolution MEPC.227(64) establishes revised effluent standards and performance test criteria for sewage treatment plants, including nitrogen and phosphorus limits applicable to special areas such as the Baltic Sea. Treated effluent must produce no visible floating solids and must not cause discoloration of surrounding waters. These standards elevate the performance bar for treatment systems and reinforce the shift toward solutions capable of meeting stricter discharge criteria without reliance on passive holding alone.
In the United States, the USCG classification framework adds another layer of decision-making complexity. Type I systems, including electrochemical or heat-based configurations, are certified for vessels under 65 feet and may allow treated black water discharge in areas that are not designated as no-discharge zones. Type II systems apply to larger inspected vessels and require more stringent biological or chemical treatment processes under 33 CFR Part 159. For US-flagged vessels on international voyages, voluntary compliance with MARPOL Annex IV can be demonstrated through a USCG Statement of Voluntary Compliance based on NVIC 1-09 guidance, particularly where treatment plants meet MEPC.227(64) or equivalent standards. This regulatory ecosystem means that product certification, operational zone eligibility, and system sizing are not peripheral considerations; they are central to market access.
Operational considerations further influence purchasing behavior. Marine sewage treatment systems commonly incorporate corrosion-resistant construction materials, including marine-grade aluminum or steel coated with ceramic-filled epoxy, to withstand the demanding conditions of black water handling. System design must also account for maintenance frequency, footprint constraints, energy consumption, and ease of integration with existing vessel infrastructure. These practical realities create a purchasing environment where specifiers evaluate not only regulatory compliance, but also serviceability, reliability, and lifecycle cost. The result is a market in which differentiation is increasingly driven by engineering robustness, certification breadth, and application-specific optimization.
Competitive Arena: Leadership, Specialization, and Strategic Positioning
The competitive landscape for marine black water treatment systems is characterized by a mix of established marine equipment manufacturers, specialized sanitation providers, and global technology groups with integrated waste management capabilities. The market exhibits a moderately concentrated structure, with the top three competitors collectively holding approximately 32.4 percent of market share and the top five firms accounting for around 48.75 percent. This concentration suggests that while scale players exert meaningful influence, there remains substantial room for specialized firms to compete on technology differentiation, application focus, and regional service strength.
Several core companies illustrate the breadth of strategic positioning within the sector. GROCO offers a portfolio encompassing heat-based Type I systems such as Thermopure for vessels under 65 feet, electrochemical ElectroScan technology that generates disinfectant from salt water, and Type III holding system configurations designed for compact and reliable sanitation in recreational and small marine applications. Raritan Engineering Company is widely recognized for its ElectroScan Type I MSD, which uses electrodes to convert salt water into a bactericide, enabling black water treatment without reliance on holding tanks in permitted discharge areas for vessels up to 65 feet. Headhunter Inc. focuses on marine sewage treatment plants and MSDs, including the TidalWave HMX platform, which is IMO MEPC.227(64) and USCG Type II certified and employs chemical oxidation, hydro-maceration, and cross-flow separation for vessels over 65 feet with capacities ranging from 50 to 10,000 US gallons per day.
Worldwide Black Water Treatment System for Boats Market
On the international stage, De Nora contributes electrolytic marine wastewater treatment through its OMNIPURE platform, which uses DSA electrode technology for oxidation and disinfection without biological media or additives, and is certified to IMO MEPC.227(64) and USCG standards. RedFox Environmental Services manufactures USCG and IMO certified marine sewage treatment units for black water across marine, offshore, and land applications, meeting MEPC.227(64) and EPA compliance requirements, with production based in Louisiana and global service support. Ahead Sanitation Systems supplies USCG Certified Type II marine sanitation devices for a broad range of workboats, tugboats, towboats, barges, yachts, and pleasure craft, emphasizing lightweight, compact, odor-free, low-maintenance aerobic designs. HAMANN AG provides advanced wastewater treatment systems, including the HL-CONT Plus series, for combined black and grey water treatment on superyachts, cruise ships, ferries, and offshore or inland vessels, with compliance for MARPOL Annex IV special areas such as Alaska and the Baltic Sea, utilizing modular designs without filters or membranes.
Additional participants further diversify the competitive field. Scienco/FAST manufactures biological marineFAST sewage treatment systems for blackwater and combined waste streams, with nearly 5,000 installations worldwide and USCG/IMO certifications serving tugs, offshore supply vessels, and commercial ships. Evac delivers integrated marine water and waste management solutions as part of a broader total concept package for vacuum collection and black water processing across multiple vessel types. Wärtsilä offers complete marine waste and wastewater treatment packages, including sewage treatment plants and membrane bioreactor systems for black water management on all types of vessels. ACO Marine specializes in tailored wastewater treatment solutions, including biological Clarimar MF systems for black water, while RWO Water Technologies supplies marine sewage treatment plants as part of pollution prevention equipment with more than 45 years in marine water treatment. H2O Inc., through its Crapzapper line, provides biological marine sanitation devices dual-certified under USCG and IMO MEPC.227(64), with over 4,500 units installed worldwide for crews ranging from 2 to 500. Detegasa rounds out the competitive landscape with high-tech water and waste management solutions designed for navy, marine, and offshore industries.
These companies are not competing on a single axis. Differentiation is emerging through certification scope, vessel class specialization, treatment methodology, corrosion-resistant engineering, and the ability to provide integrated service and support across global fleets. Recent market activity reinforces this competitive intensity with a visible emphasis on trade presence and application-specific positioning. In February 2026, Raritan Engineering Company participated in the Miami International Boat Show, highlighting proven marine sanitation designs including ElectroScan systems. Ahead Sanitation Systems has an active exhibition calendar through the end of 2026, with scheduled showcases of USCG Certified Type II systems at the Inland Marine Expo, the Pacific Marine Expo, and the International WorkBoat Show, underscoring a deliberate push to strengthen visibility across workboat and commercial marine channels. In December 2025, industry coverage from Superyacht Times featured advanced wastewater treatment systems from ACO Marine and HAMANN, addressing black water volumes of up to 500 liters per person per day and the need for tailored sewage management spanning collection through discharge. These developments point to a competitive environment in which market access is being reinforced through demonstration, application focus, and compliance-aligned product narratives.
Report Scope: What Decision-Makers Will Gain
This market research report is designed to move beyond descriptive market overviews and deliver a structured, decision-ready intelligence framework. Clients will gain access to a detailed analysis of market sizing and forecast pathways, supported by historical context and forward-looking projections that clarify growth mechanics rather than simply reporting endpoints. The report examines segmentation dynamics across technology type, end-use application, and regional deployment, enabling users to assess where demand is concentrated and how purchasing behavior varies by segment.
The competitive analysis component provides a structured assessment of leading participants, their product positioning, certification portfolios, and strategic activity. Rather than presenting a static company list, the report contextualizes competitive behavior within the regulatory and operational realities that shape procurement decisions. This allows readers to evaluate not only who is active in the market, but how different players are aligning their offerings with compliance intensity, vessel class requirements, and regional service expectations.
The regulatory and operational sections integrate international and national compliance frameworks into a practical market context, helping users understand how effluent standards, discharge restrictions, and certification pathways influence technology selection, retrofit demand, and product design priorities. In addition, the report addresses material and engineering considerations that affect product durability, maintenance requirements, and lifecycle performance, providing context that is directly relevant to specification, procurement, and risk assessment.
To support strategic planning, the report also maps recent industry developments, including trade show activity, product showcases, and sector-specific coverage that signal how companies are positioning themselves across leisure, commercial, and superyacht applications. This combination of macro-level market structure and micro-level competitive intelligence creates a comprehensive reference point for strategic planning, investment evaluation, and market-entry analysis.
Strategic Application: How to Use This Intelligence in 2026
For organizations operating in or seeking to enter the marine black water treatment sector, the value of this research lies in its ability to connect market structure to action. Executives can use the forecast framework to align product roadmaps with anticipated demand growth, prioritize segment focus based on compliance-driven procurement cycles, and evaluate where technology differentiation offers the strongest competitive leverage. Suppliers can assess how certification breadth, system sizing, and corrosion-resistant engineering influence spec-in decisions across vessel classes, and identify where service and support capabilities may serve as differentiators in fragmented regional markets.
Procurement and specification teams can leverage the regulatory and operational analysis to better understand compliance eligibility, discharge zone constraints, and the practical implications of system type selection for different vessel profiles. Investors and strategic partners can use the market concentration and competitive positioning data to evaluate the intensity of rivalry, the degree of specialization in the supplier base, and the potential for consolidation or technology-led disruption. In all cases, the report is designed to reduce ambiguity and support decisions grounded in verified market structure rather than assumption.
Conclusion: Turning Market Complexity into Strategic Advantage
The worldwide black water treatment system for boats market is entering a phase in which regulatory precision, application specialization, and engineering reliability are increasingly decisive. With a 2025 base year valuation of approximately 535.4 million USD and a projected 2032 market size approaching 854.13 million USD at a 6.89 percent CAGR, the sector offers meaningful growth potential, but that growth is distributed across a nuanced competitive and regulatory landscape. Success in this environment requires more than awareness of overall market expansion; it demands a detailed understanding of technology pathways, certification dynamics, end-use behavior, regional variation, and competitive positioning.
PW Consulting's Worldwide Black Water Treatment System for Boats Market report is structured to deliver that understanding in a form that is immediately useful for strategic planning and commercial decision-making. To access the full dataset, segmentation breakdowns, competitive assessments, and detailed forecast architecture, we invite you to explore the complete report on our website. The full intelligence package provides the depth and granularity required to translate market awareness into actionable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Black Water Treatment System for Boats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global HTML5 Games Market to Hit $73.67B Revenue by 2032 Amid 12.45% CAGR
By pmarketresearch, 2026-09-16
Navigating the HTML5 Games Market: Strategic Intelligence for 2026 and Beyond
The global gaming landscape is undergoing a quiet but profound restructuring. As device fragmentation intensifies, user acquisition costs climb, and platform gatekeepers tighten their control, HTML5 games have emerged as a decisive infrastructure layer for brands, publishers, and developers seeking frictionless, cross-device player engagement. Our latest research report, Worldwide HTML5 Games Market, maps this transformation with the precision required to turn market momentum into executable strategy. Built on a rigorous historical base spanning 2020 through 2025 and extended across a forecast window to 2032, the study is designed for executive teams that need more than headline growth figures—they need a clear operating manual for 2026 decision-making.
Worldwide HTML5 Games Market
Worldwide 2D Game Market
The market has already crossed a meaningful threshold. Total industry revenue reached approximately 32.4 billion USD in 2025, up from 15.2 billion USD in 2020, reflecting a compound annual growth rate of 12.45 percent over the historical period. Rather than treating this trajectory as a simple growth story, our analysis treats it as a structural signal: the browser-based gaming channel is maturing into a standalone commercial ecosystem with distinct monetization logic, distribution dynamics, and competitive rules. Looking ahead, the forecast window suggests continued expansion toward roughly 73.7 billion USD by 2032, with the most consequential strategic question no longer being whether HTML5 games will scale, but how organizations can position themselves to capture durable share within an increasingly crowded field.
That is precisely the question this report is built to answer.
Why This Report Matters for 2026 Strategy
Many market summaries stop at top-line projections. That approach is useful for broad awareness, but it is insufficient when 2026 planning requires allocation decisions across product roadmaps, partnership pipelines, regional priorities, and monetization design. This report is structured to support those choices. It provides a decision-grade view of how value is being created, moved, and captured across the HTML5 gaming value chain, with particular attention to the channels, revenue models, and competitive behaviors that are reshaping returns.
For publishers and brand teams, the study clarifies where discovery is happening and how player attention is being converted into recurring engagement. For developers and technology providers, it maps the practical realities of engine choice, distribution reach, and build-vs-partner trade-offs. For investors and corporate strategy groups, it frames market concentration, platform leverage, and the evolving economics of cloud-supported browser gaming. Throughout, the analysis is anchored in actionable segmentation rather than abstract narratives, enabling readers to interrogate the market from the perspective of their own operational constraints.
Equally important, the report integrates the operational pressure points shaping 2026. Web-based gaming does not exist in isolation. It depends on data infrastructure, connectivity economics, and a regulatory environment that is becoming more active by the quarter. By embedding these factors into the market narrative, the study helps leaders anticipate downstream effects on cost structures, deployment timing, and channel design before those pressures become embedded in quarterly results.
Market Architecture: Channels, Monetization, and Regional Logic
A defining feature of the HTML5 games market is that growth is not evenly distributed across channels or revenue models. It is concentrated where frictionless access and scalable monetization intersect. Our segmentation analysis traces how different distribution pathways and revenue architectures contribute to overall market formation, without treating any single pathway as a universal solution.
Distribution dynamics are especially important in 2026 because the channel mix determines both reach and commercial control. The report examines how social media mini-programs, mobile web browsers, desktop game portals, and messaging-platform integrations each shape acquisition velocity, session design, and retention potential. Instead of presenting any one channel as inherently superior, the analysis explains where each pathway creates advantage, what operational capabilities it demands, and how publishers should sequence channel investment based on audience type, product format, and monetization goals.
The same discipline applies to revenue design. In-game advertising, in-app purchases, and subscription and licensing models each carry distinct value-creation mechanics. The report analyzes how these models interact with user behavior, content genre, and platform economics, highlighting why many successful HTML5 portfolios are moving toward layered monetization rather than relying on a single stream. This matters for 2026 because margin stability increasingly depends on matching revenue architecture to audience intent, session length, and content cadence.
Regional dynamics are treated with equal care. The study considers how local device behavior, digital consumption patterns, platform ecosystems, and commercial norms shape adoption and monetization outcomes across major geographies. Rather than reducing regional performance to static share percentages, the report explains the structural drivers that determine where demand is forming, which audience segments are expanding fastest, and how organizations should calibrate market entry, localization, and partnership strategies accordingly. In practice, this gives leaders a more reliable basis for prioritizing expansion than top-line rankings alone.
Competitive Landscape: Platforms, Engines, and the New Center of Gravity
The HTML5 ecosystem is not defined by a single business model. It spans distribution platforms, publishing operations, engine and tooling providers, and development studios. That diversity is one reason the market remains both dynamic and strategically complex. Our competitive analysis maps these roles and shows how value is accumulating across the ecosystem, with special attention to organizations that are already shaping industry direction.
Distribution and publishing platforms are central to the market's current architecture. Companies such as GameDistribution and CoolGames illustrate how scale, cross-platform reach, and IP integration can create powerful discovery pipelines for browser-based casual games. Their influence goes beyond traffic volume: they structure how developers access audiences, how publishers assemble portfolios, and how licensed content is adapted for instant-play environments. GamePix similarly reflects the continued importance of unifying distribution across websites, applications, and carrier-linked channels, especially where regional access patterns differ from purely app-centric markets.
A notable signal in the current cycle is the strengthening of IP-led browser gaming strategies. CTW Cayman, operating through its G123.jp platform, has expanded rapidly as an anime IP-based HTML5 gaming operator, building a multi-title portfolio and extending its reach through a 2025 NASDAQ listing. Its 2025 capital raise underscores how market participants are funding platform growth, portfolio expansion, and geographic targeting across the United States, Europe, and Southeast Asia. This trajectory matters because it shows that browser-compatible gaming is increasingly being treated as a serious IP monetization channel rather than a peripheral marketing format.
On the technology side, the report examines the tooling landscape that enables HTML5 creation at scale. Engines and frameworks such as PlayCanvas, Phaser, and Construct highlight different development philosophies: high-end 3D browser experiences, widely adopted 2D JavaScript workflows, and accessible no-code or low-code creation paths. The strategic implication is that the market now supports a broad spectrum of production models, from rapid casual development to more ambitious interactive web applications. That flexibility is reshaping who can enter the market, how quickly products can be shipped, and what kinds of experiences are commercially viable in browser environments.
The competitive set also includes development studios with strong regional footprints and specialized capabilities. Firms based in India, Bangladesh, Italy, New Zealand, and other markets are increasingly active in HTML5 development, licensing, and cross-platform browser experiences. Their presence reflects a broader trend: HTML5's accessibility and deployment simplicity continue to enable distributed development models, which in turn affect pricing dynamics, time-to-market, and the strategic importance of production partnerships. The study places these players in context so readers can evaluate not only who competes, but where competitive advantage is actually being built.
Dynamics Shaping 2026: Momentum, Events, and Infrastructure Realities
Market growth does not occur in a vacuum. It is reinforced or constrained by product events, community activity, and the underlying economics of digital infrastructure. The report ties these forces together so leaders can distinguish durable trends from temporary noise.
Recent product activity shows how established titles and platform ecosystems are continuing to lean into HTML5 as an accessibility-first distribution strategy. Sustained rollout of browser-based editions of well-known game franchises illustrates the commercial appeal of instant access across devices, removing download friction while preserving broad audience reach. At the same time, platform-level performance milestones—such as high-volume play counts achieved through iterative seasonal updates and variant testing—demonstrate that HTML5 success increasingly depends on post-launch optimization, content cadence, and distribution refinement rather than launch-day visibility alone.
Community-driven development activity also remains a meaningful indicator of ecosystem vitality. Events focused on building and shipping HTML5 games create a visible feedback loop between experimentation, tooling improvement, and creative output. They also reflect the market's openness to rapid iteration, which is one reason the channel continues to attract both independent developers and commercial teams seeking efficient ways to test mechanics, audience response, and monetization concepts.
At the same time, the report addresses a less visible but strategically critical factor: the cost and regulatory environment surrounding the infrastructure that supports browser-based services. As cloud-supported web gaming scales, it intersects with a fast-evolving policy landscape around data center energy use, power procurement, and infrastructure cost recovery. In the United States, regulatory attention has intensified around the electricity demands associated with large-scale digital infrastructure, including proposals and state-level actions that differentiate large-load users through specialized rate structures. Policy discussions in 2026 have also promoted voluntary compacts under which major operators would cover a substantial share of new power generation and transmission upgrade costs.
For HTML5 gaming organizations, these dynamics are not abstract. They influence hosting economics, performance expectations, scaling assumptions, and the long-term cost base of always-on web services. By incorporating this context directly into the market analysis, the report helps readers factor infrastructure exposure into strategic planning rather than treating it as a downstream compliance issue.
What the Report Delivers: A Practical Intelligence Toolkit
The Worldwide HTML5 Games Market study is built to support concrete decisions. Its structure is designed to move from strategic context to operational insight, giving readers a comprehensive but usable reference for 2026 planning. Among its core components are:
- Historical market sizing and forecast modeling that traces revenue development from 2020 through 2032, with a clear view of growth momentum and projection logic.
- Segmentation analysis across distribution channels, revenue models, and regional dynamics, presented to support channel prioritization, monetization design, and market-focus decisions.
- Competitive profiling of leading platforms, publishers, engines, and development studios, including recent corporate developments, expansion moves, and product-level activity shaping the market.
- Industry dynamics coverage that connects gaming strategy with infrastructure cost pressures, regulatory direction, and ecosystem events affecting browser-based services.
- Strategic interpretation intended to help leaders translate market structure into portfolio decisions, partnership choices, and investment prioritization.
The report is intentionally designed to bridge market intelligence and execution. Rather than leaving readers with isolated figures, it frames the market as a set of interdependent choices: where to compete, how to monetize, which distribution relationships matter most, and how to prepare for the operational realities that will shape costs and scalability over the forecast period.
Using the Research for 2026 Decision-Making
The strongest value of this study lies in its use as a decision framework. For product and publishing leaders, it offers a basis for evaluating which channels and monetization models align with specific game formats and audience behaviors. For technology and engine selection teams, it clarifies the trade-offs between rapid development workflows and more advanced web-based interactive experiences. For partnership and M&A teams, it helps identify where platform leverage, distribution reach, and IP-driven browser strategies are creating durable advantages. For executive planning groups, it provides a structured way to integrate market growth expectations with infrastructure and regulatory risk.
In a market growing at a sustained double-digit pace, speed alone is not a strategy. The more durable advantage comes from understanding where value concentrates, how competitive positions are forming, and which assumptions about distribution, monetization, and infrastructure will hold up under scrutiny. This report is built to support precisely that kind of planning.
Access the Full Intelligence
The overview above highlights the strategic logic and scope of the worldwide HTML5 games market analysis, but the actionable detail—precise segmentations, competitive positioning, regional dynamics, and forward-looking market modeling—is developed fully within the complete report. For teams preparing 2026 investments, product roadmaps, and expansion strategies, the full document provides the evidence base needed to move from market awareness to confident decision-making.
To explore the complete findings, segmentation depth, and competitive analysis, request or download the full Worldwide HTML5 Games Market research. Doing so will give your team the structured intelligence necessary to navigate a rapidly maturing market with clarity, discipline, and strategic intent.
For detailed analysis of this topic, please visit the official page: Worldwide HTML5 Games Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Digital TV Modulator Market to Reach $855.55M by 2032, 4.81% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Connected Era: Inside the Worldwide Multi-Channel Digital TV Modulator Market 2026-2032
The global telecommunications and broadcast infrastructure landscape is undergoing a profound transformation. As bandwidth demands escalate and hybrid distribution models become the norm, the Worldwide Multi-Channel Digital TV Modulator market stands at a critical inflection point. Our latest market research, Worldwide Multi-Channel Digital TV Modulator Market, provides a comprehensive, data-driven examination of this vital sector, offering executives and strategic planners the clarity needed to navigate the complexities of 2026 and beyond. This report is not merely a collection of statistics; it is a strategic compass designed to illuminate market trajectories, competitive maneuvers, and the regulatory currents shaping the industry.
For decision-makers evaluating capital allocation, technology roadmaps, or market entry strategies, understanding the macro-environment is paramount. The market has demonstrated consistent growth over the past half-decade, reflecting the sustained demand for reliable, high-quality digital signal distribution across diverse sectors. The total revenue for the base year 2025 is established at 615.8 million USD, building upon a robust historical trajectory that saw the market expand from 492.3 million USD in 2020. This growth underscores the essential role that digital TV modulators play in modernizing infrastructure, whether for traditional broadcast headends, hospitality networks, or emerging hybrid IPTV environments. The forecast period from 2026 to 2032 anticipates continued expansion, with the market projected to reach 855.55 million USD by the end of the outlook window. This evolution is driven by a Compound Annual Growth Rate (CAGR) of 4.81 percent, signaling a steady, maturing market that rewards strategic positioning and technological agility.
Decoding the Market Architecture
A superficial glance at aggregate figures often masks the nuanced realities of supply and demand. Our analysis dissects the market through multiple critical dimensions, providing a granular view of where value is created and how different standards and applications influence overall performance. The technology landscape is segmented by modulation standards, reflecting the global diversity in broadcast protocols. The market encompasses DVB-T/DVB-T2, DVB-C/DVB-C2, ATSC/ATSC 3.0, and ISDB-T and DTMB standards. Each standard commands a distinct share of the revenue mix, influenced by regional adoption patterns, legacy infrastructure considerations, and the speed of next-generation transitions such as the rollout of ATSC 3.0 or the persistence of DVB-C in cable environments. Understanding the relative weight of these standards is essential for vendors tailoring product portfolios and for operators planning migration paths.
Geographically, the market exhibits a balanced but dynamic distribution. Revenue streams are dispersed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The Asia Pacific region currently reflects the largest revenue contribution, driven by rapid urbanization, expanding hospitality sectors, and extensive campus and community network deployments. North America and Europe follow, characterized by mature markets where incremental growth is fueled by high-density headend upgrades, 4K transport stream capabilities, and the integration of multi-channel modulation into hybrid broadcast-broadband workflows. Emerging regions in Latin America and the Middle East and Africa present distinct opportunities tied to infrastructure development and the modernization of cable and broadcasting networks. Our report provides a detailed regional analysis that goes beyond top-line numbers, exploring the specific drivers, challenges, and growth vectors within each territory.
Application segmentation further reveals the versatility of multi-channel digital TV modulators. The market serves a wide array of end-users, with Hospitality and Healthcare representing the largest application segment. This dominance is attributable to the need for reliable, customizable television distribution in hotels, medical facilities, and assisted living centers, where multi-channel modulators enable the delivery of localized content, information channels, and entertainment services over existing coaxial or RF infrastructure. Broadcasting and Cable TV Operators form another major pillar, leveraging high-density modulation solutions to manage signal distribution, headend efficiency, and the transition to advanced compression and transmission formats. Residential and Community Systems, as well as Commercial and Educational Facilities, round out the application landscape, each with unique requirements regarding scalability, ease of integration, and service flexibility. By quantifying the revenue contribution of each application, the report empowers stakeholders to align their product development and sales strategies with the most lucrative and rapidly evolving verticals.
Competitive Dynamics and Strategic Positioning
The competitive landscape of the multi-channel digital TV modulator market is characterized by a mix of specialized innovators, established broadcast equipment manufacturers, and regional players with strong local footprint. Our analysis profiles key companies that are shaping the industry, evaluating their product portfolios, technological capabilities, geographic reach, and strategic positioning. Thor Broadcast and Pro Video Instruments (VeCOAX) exemplify the focus on multi-channel HDMI to RF conversion solutions, offering systems that multiplex multiple HDMI or SDI sources into digital TV channels for CATV, hospitality, and broadcast distribution. Blonder Tongue Laboratories continues to serve professional video distribution and MATV/SMATV networks with tailored modulation hardware. In the Asian market, DIBSYS Technologies, Souka / Dingshengwei Electronics, Softel Optic, and Gospell Digital Technology provide a broad range of encoder modulators, multi-channel RF solutions, and headend systems that support DVB, ATSC, ISDB-T, and DTMB standards, often with added features like OSD and QR code insertion or simultaneous IPTV output. WISI Communications and Harmonic Inc. bring high-density encoding and modulation expertise to cable and broadcast headends, while Rohde & Schwarz contributes advanced test and broadcast equipment, including multi-channel DVB modulators designed for high-density deployments and 4K transport streams.
Market concentration metrics indicate a moderately fragmented environment, with the top three companies holding a combined share of 21.4 percent and the top five firms accounting for 34.85 percent. This structure suggests that while leading players exert influence, there is ample room for niche differentiation, regional specialization, and technology-driven disruption. Recent corporate activities highlight the dynamic nature of this landscape. In March 2025, Harmonic Inc. completed the acquisition of Nexstreaming, a move designed to strengthen its multi-channel digital TV modulation portfolio and accelerate integration with next-generation headend systems. This acquisition signals a strategic emphasis on consolidating capabilities to address the increasing complexity of hybrid broadcast and IPTV workflows. In May 2025, Imagine Communications announced a strategic partnership with Teleste to deliver integrated encoding, transcoding, and DVB modulator solutions, reflecting the industry's push toward seamless convergence of broadcast and IP-based distribution. Furthermore, in June 2025, Rohde & Schwarz introduced the R&S MMD series, a new line of multi-channel DVB modulators tailored for high-density headend deployments and 4K-capable transport streams. These developments underscore the importance of staying abreast of M&A activity, partnerships, and product launches, as they reshape competitive advantages and open new avenues for collaboration.
Navigating Regulatory Currents and Infrastructure Realities
Market growth does not occur in a vacuum; it is deeply influenced by regulatory frameworks, spectrum policy, and the economics of infrastructure deployment. Our report integrates critical industry context to help stakeholders anticipate external forces that may impact demand, compliance costs, and technology adoption. In the United States, regulatory decisions continue to shape the broadband and broadcast ecosystem. The U.S. Court of Appeals for the Sixth Circuit invalidated the FCC's 2024 Open Internet Order, ruling that broadband constitutes an information service under the Communications Act. This ruling has implications for how video distribution services interact with broadband networks and may influence the strategic planning of operators that rely on hybrid delivery models. Simultaneously, the FCC reauthorization of spectrum auction authority through the Big Beautiful Bill enables new proceedings for upper C-band spectrum auctions and the modernization of licensing for upper-microwave spectrum. These developments are highly relevant for broadcast and cable infrastructure, as spectrum availability and licensing conditions directly affect the deployment of digital TV modulation systems and the efficiency of signal distribution networks.
Infrastructure costs and technological trends also play a pivotal role. The datacom optical component market for fiber optics in data centers and telecom backhaul is projected to exceed 16 billion USD in 2025, driven by 400G and 800G shipments and AI-related interconnect demand. While this figure pertains to a broader optical market, it reflects the accelerating investment in high-capacity transmission networks that underpin modern digital TV signal distribution. As operators upgrade backhaul and edge infrastructure, the integration of multi-channel modulators with robust, high-throughput transport layers becomes increasingly important. Additionally, U.S. broadband policy emphasizes fiber deployment incentives under programs like BEAD, while addressing outdated copper line maintenance regulations that increase operational costs for hybrid video distribution systems. These policy dynamics highlight the need for cost-effective, future-proof modulation solutions that can adapt to evolving network architectures and regulatory requirements.
Operational Excellence: A Roadmap for 2026 Decision-Making
The Worldwide Multi-Channel Digital TV Modulator Market report is structured to deliver actionable intelligence. Beyond the macro analysis, the document provides a detailed examination of market drivers, restraints, and opportunities. It explores how factors such as the demand for high-density headend equipment, the transition to ATSC 3.0 and advanced DVB standards, the expansion of hospitality and healthcare networks, and the integration of IP-based workflows are shaping purchasing decisions and product specifications. The report also assesses challenges, including supply chain considerations, the cost of legacy system migration, and the competitive pressure from emerging regional manufacturers. By mapping these forces, the study enables readers to identify where to invest, which segments offer the highest growth potential, and how to mitigate risks associated with regulatory shifts or technology transitions.
TV Transmitter Market
A core strength of this research lies in its segmentation depth. Readers gain access to a comprehensive breakdown of the market by standard, region, and application, with revenue figures and growth projections that illuminate the relative performance of each segment. This granularity is essential for product managers seeking to prioritize R&D efforts, for sales teams targeting specific verticals, and for investors evaluating market attractiveness. The report also includes profiles of key companies, analyzing their strategies, recent developments, and positioning within the value chain. By synthesizing quantitative data with qualitative insights, the study provides a holistic view of the competitive environment and the strategic moves that are redefining industry leadership.
Why This Research Matters Now
As the market advances toward the 2032 horizon, the decisions made in 2026 will have lasting consequences. The CAGR of 4.81 percent indicates a market that is neither hyper-volatile nor stagnant, but rather one that rewards foresight, precision, and adaptability. Companies that understand the interplay between standards evolution, regional demand patterns, application-specific requirements, and regulatory developments will be best positioned to capture value. Our report equips stakeholders with the analytical foundation to make those decisions confidently. Whether you are evaluating a product launch, assessing a partnership, planning a regional expansion, or benchmarking your competitive standing, this research offers the evidence-based insights needed to move forward with clarity.
The media and broadcast technology sector is crowded with data, but not all data translates into strategic advantage. The Worldwide Multi-Channel Digital TV Modulator Market study is designed to bridge that gap. It transforms raw market figures into a coherent narrative of growth, competition, and opportunity. By focusing on the segments, standards, and dynamics that truly matter, the report helps organizations cut through noise and concentrate on the levers that drive performance. The inclusion of recent corporate developments, regulatory analysis, and infrastructure trends ensures that the intelligence is current and contextually rich, reflecting the realities of the 2026 operating environment.
Worldwide Multi-Channel Digital TV Modulator Market
For executives and analysts who require a deeper dive into specific regional trajectories, application-level revenue breakdowns, or detailed company benchmarking, the full report provides the comprehensive dataset and expert commentary necessary to support high-stakes decision-making. The insights presented here are a preview of the strategic value contained within the complete study. We invite you to access the full report to unlock the complete spectrum of market intelligence, from granular segmentation data to forward-looking scenario analysis, and to ensure that your organization is equipped with the knowledge needed to thrive in the evolving global multi-channel digital TV modulator market.
In an industry where technology cycles accelerate and regulatory landscapes shift, information is currency. This research is crafted to deliver that currency in a form that is precise, actionable, and aligned with the strategic priorities of modern enterprises. As you plan for the years ahead, let this study serve as your reference point for understanding where the market is headed, who is leading the way, and how to position your organization for sustained success.
For detailed analysis of this topic, please visit the official page: Worldwide Multi-Channel Digital TV Modulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Uniform Rental Market Hits $16.5B in 2025, Forecasts 4.25% CAGR to $22.07B by 2032
By pmarketresearch, 2026-09-16
Navigating the Uniform Rental Landscape: Strategic Intelligence for 2026 and Beyond
The uniform rental market stands at a pivotal juncture as organizations navigate shifting operational cost structures, evolving compliance requirements, and an increasingly consolidated competitive environment. As enterprises recalibrate their procurement strategies and workplace service expectations, the ability to anticipate demand shifts, evaluate supplier risk, and align rental agreements with long-term operational goals has never been more critical. Our latest Uniform Rental Market study delivers a comprehensive, forward-looking assessment designed specifically to equip executive decision-makers, procurement leaders, and industry strategists with the analytical rigor required to navigate the 2026 business landscape and the years ahead.
This research is structured not as a static snapshot, but as a dynamic decision-support framework. It maps the trajectory of a sector that has demonstrated remarkable resilience through recent macroeconomic volatility, while simultaneously confronting structural pressures ranging from supply chain reconfiguration to labor cost dynamics. By synthesizing historical performance patterns with rigorously modeled forward projections, the report provides a clear lens through which organizations can benchmark their positioning, identify whitespace opportunities, and mitigate exposure to emerging market disruptions.
Market Scale and Trajectory: A Foundation for Strategic Planning
Understanding the magnitude and momentum of the uniform rental sector is the first step toward embedding it effectively within corporate strategy. Over the historical window spanning 2020 through 2025, the market navigated a period of recovery, adaptation, and measured expansion. After moving past initial operational disruptions, the industry demonstrated a steady upward trajectory, with total market revenue climbing to approximately $16.5 billion by the 2025 base year. This progression reflects the enduring institutional demand for managed workwear solutions across sectors that prioritize standardization, compliance, hygiene, and operational efficiency.
Looking ahead to the 2026–2032 forecast period, the market is positioned for continued expansion at a compound annual growth rate of 4.25 percent. This growth path is not merely a linear extrapolation; it reflects the compounding effect of sustained enterprise adoption, incremental sectoral demand, and the gradual integration of advanced logistics and facility service models into traditional uniform rental frameworks. By the close of the forecast horizon in 2032, total market revenue is projected to approach $22 billion, signaling a sector that continues to embed itself more deeply into the operational fabric of modern enterprises.
For strategic planners, these macro-level indicators serve as a critical baseline. They underscore that uniform rental is not a commoditized, static service category, but a dynamic commercial ecosystem influenced by end-user procurement cycles, regulatory shifts, and competitive restructuring. Leaders who internalize this trajectory can better time contract renewals, evaluate capital allocation toward workplace service partnerships, and anticipate how broader economic conditions will shape pricing power and service expectations across the value chain.
Workwear and Uniforms Market
Core Segments and Demand Drivers: Where Growth Converges
The uniform rental ecosystem is shaped by multiple intersecting dimensions, each carrying distinct operational implications for providers and buyers alike. At the highest level, the market divides into several foundational categories that dictate product specifications, service logistics, and compliance requirements. Industrial uniforms remain the dominant segment, reflecting the persistent need for durable, safety-aligned workwear across manufacturing environments, warehousing operations, and heavy-duty service applications. Food and beverage uniforms represent another substantial pillar, driven by stringent hygiene standards, brand consistency requirements, and high-turnover operational models that favor rental over ownership. Healthcare and medical wear constitutes a third critical pillar, where regulatory compliance, infection control protocols, and specialized fabric performance create a highly differentiated service environment.
These categorical divisions are further amplified by application-specific demand patterns. Manufacturing and industrial environments remain the largest operational anchor for uniform rental programs, supported by the practical advantages of centralized laundering, inventory management, and replacement logistics. Healthcare facilities form a second major demand center, where uniform and clinical wear programs intersect with patient safety mandates and staff standardization initiatives. Hospitality and food services continue to represent a meaningful application segment, driven by brand image management, linen and uniform integration, and the operational complexity of multi-site service delivery. Commercial and retail services round out the broader application landscape, where appearance standards, employee branding, and seasonal staffing fluctuations influence rental program sizing and rotation models.
For enterprise decision-makers, the strategic value lies in recognizing how these segments interact with organizational priorities. A manufacturing firm evaluating vendor consolidation must weigh industrial-grade durability and safety compliance against total cost of ownership. A healthcare network designing a standardized clinical wear program must navigate fabric certifications, laundering validation, and staff comfort alongside contract flexibility. A hospitality operator managing multi-property uniforms and linens must reconcile brand consistency with rapid replacement cycles and regional service availability. Our report dissects these application-level dynamics in detail, providing the analytical scaffolding needed to match rental program design with operational reality.
Uniform Rental Market
Competitive Architecture and Consolidation Pressures
The competitive dynamics of the uniform rental market have entered a phase of pronounced restructuring. Market concentration metrics indicate a moderately consolidated landscape, with the top three providers collectively accounting for approximately 45.5 percent of total market revenue and the top five firms capturing roughly 58.2 percent. This concentration reflects the operational scale advantages inherent in uniform rental logistics, including route optimization, centralized laundering capacity, national delivery networks, and the ability to offer integrated facility service portfolios.
Several established players define the current competitive frontier. Cintas Corporation has built a comprehensive platform spanning uniform rental, facility services, and workplace supplies, serving diverse end markets with broad program flexibility. UniFirst Corporation delivers uniform rental and facility solutions to a substantial daily workforce footprint, emphasizing workwear, floor mats, and hygiene-related service offerings across multiple sectors. Vestis Corporation operates as a major North American provider with full-service uniform care, delivery, and maintenance infrastructure. Aramark integrates uniform rental within a broader facilities management umbrella, maintaining a particularly visible presence in healthcare, hospitality, and industrial environments. Alsco Uniforms brings more than a century of experience in work apparel, laundering, and linen supply, while Mission Linen Supply and Prudential Overall Supply demonstrate the continued importance of regionally anchored and specialized service models across Western markets and cleanroom or facility-specific applications.
The strategic landscape is now being reshaped by transformative consolidation moves. A landmark acquisition agreement announced in March 2026 will see Cintas acquire UniFirst in a transaction valued at $5.5 billion, a move explicitly designed to expand service capabilities and deepen workday solutions across combined client portfolios. With closing expected in the second half of 2026, this development will meaningfully reduce the number of major competitors in the North American uniform rental market and alter the competitive calculus for both suppliers and enterprise buyers. Organizations evaluating multi-year rental partnerships must now factor in potential service integration timelines, pricing strategy shifts, and the broader implications of a more concentrated supplier base on negotiation leverage and program customization.
Recent industry survey data reinforces the sense of measured momentum. The Q1 2026 Uniform and Linen Services Industry Survey, conducted in partnership with Robert W. Baird & Co., indicated steady growth with rental revenues performing above expectations for many respondents. At the same time, employment-driven wearer growth remained largely neutral in late 2025 surveys, pointing to a market where revenue expansion is increasingly driven by pricing discipline, service bundling, and retention rather than raw headcount expansion alone. These structural nuances are central to the competitive analysis presented in the full study.
Operational Dynamics and External Pressures
No strategic assessment of the uniform rental market is complete without confronting the external forces that shape cost structures, service design, and supplier resilience. The industry remains highly labor-dependent, relying extensively on route service representatives and laundry operations personnel to maintain service quality, delivery reliability, and garment lifecycle management. This labor intensity means that wage dynamics, workforce availability, and operational efficiency initiatives directly influence program economics and, by extension, contract pricing and service-level commitments.
Simultaneously, regulatory and trade environments have introduced new cost pressures. Revised U.S. tariffs on imported textiles and protective gear components implemented in 2025 have begun to pressure cost structures for uniform rental providers, prompting a broader reassessment of supplier diversification and sourcing strategies. For enterprises locked into long-duration rental agreements, these dynamics can affect garment replacement cycles, availability of specialized protective components, and the pace at which providers pass through cost adjustments. Understanding how suppliers are adapting their procurement footprints and inventory strategies is therefore essential for risk-aware contract design.
These operational and external pressures do not exist in isolation. They intersect with broader market dynamics, including the pace of consolidation, regional service density, and the growing expectation that rental providers function as integrated workplace service partners rather than simple garment lessors. Providers that successfully align logistics efficiency, compliance assurance, and flexible program design are best positioned to defend margins and retain enterprise accounts. Conversely, buyers that fail to evaluate supplier resilience, labor model sustainability, and sourcing diversification risk encountering service variability or unexpected cost shifts over the life of their contracts.
Inside the Report: Analytical Depth for Actionable Decisions
Our Uniform Rental Market study is engineered to translate complex market signals into clear, actionable intelligence. Rather than offering a superficial overview, the report delivers a multi-layered analytical architecture designed for executive review, procurement planning, and competitive benchmarking. The full study includes a detailed market sizing framework that traces historical revenue evolution and forward projections across the entire forecast horizon, providing a reliable baseline for capacity planning, investment prioritization, and demand forecasting.
The segmentation analysis goes beyond aggregate figures to examine how distinct uniform categories and application environments behave under varying operational and economic conditions. Readers gain access to structured assessments of demand drivers, replacement cycles, compliance dependencies, and service intensity across industrial, healthcare, food and beverage, hospitality, and commercial use cases. This segmented perspective enables decision-makers to isolate the most relevant growth vectors for their specific operating context and avoid the trap of treating the uniform rental market as a monolithic category.
The competitive intelligence section provides a systematic evaluation of leading providers, their service portfolios, geographic footprints, and strategic positioning. It examines how major operators differentiate through logistics scale, integrated facility services, specialized garment programs, and regional coverage models. The analysis also maps the implications of recent consolidation activity, offering a forward-looking assessment of how market concentration may influence pricing behavior, service innovation, and buyer negotiation dynamics over the coming years.
Complementing the structural analysis, the report incorporates an external dynamics review that addresses tariff impacts, labor cost sensitivities, industry survey signals, and the evolving expectation set around provider reliability and service integration. By linking these macro and operational factors directly to rental program performance, the study equips leaders with the context needed to stress-test supplier relationships, anticipate cost pressure transmission, and design contract frameworks that balance flexibility with long-term stability.
Why This Research Matters for 2026 Decision-Making
The strategic value of this study lies in its ability to convert market complexity into decision-ready clarity. In 2026, uniform rental procurement is no longer a routine administrative function; it is a strategic lever that touches workforce compliance, brand presentation, operational continuity, and total cost management. The convergence of a moderately concentrated supplier base, transformative consolidation, evolving trade and labor conditions, and steady demand growth creates an environment where informed procurement strategy can yield measurable competitive advantage.
Enterprises that engage with this research will be better positioned to evaluate vendor consolidation proposals, benchmark existing rental agreements against market trajectories, identify segments with the most favorable growth-to-risk profiles, and construct procurement roadmaps aligned with both operational needs and financial discipline. Suppliers and investors, meanwhile, will gain a clearer view of where service differentiation is most valued, how concentration is reshaping competitive incentives, and which application areas offer the strongest pathways for sustained expansion.
The complete Uniform Rental Market report expands significantly on the themes introduced here, delivering the detailed sizing architecture, segmented demand analysis, competitive evaluations, and dynamic risk assessments required for high-stakes decision-making. To access the full dataset, scenario frameworks, and provider-level strategic breakdowns, we invite you to explore the complete study on our website. In a market defined by consolidation, cost complexity, and steady structural growth, comprehensive intelligence is not simply an asset. It is the foundation of resilient strategy.
For detailed analysis of this topic, please visit the official page: Uniform Rental Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Sheep Milk Market Hits $6.28B in 2025, Projected to Reach $12.12B by 2032 at 9.85% CAGR
By pmarketresearch, 2026-09-16
Navigating the White Gold: Strategic Imperatives in the Global Sheep Milk and Infant Formula Market Through 2032
The global dairy landscape is witnessing a structural shift, driven by evolving nutritional science and a premiumization of consumer demand. At the forefront of this transformation is the sheep milk segment, particularly its application in infant formula. For corporate strategists, category managers, and investor relations teams, the period from 2026 through 2032 represents a decisive window of market consolidation and value creation. This insight serves as a strategic primer to our comprehensive Worldwide Sheep Milk and Infant Formula Market research, designed to equip decision-makers with the granular intelligence required to navigate a sector defined by high barriers to entry, complex regulatory environments, and robust compound growth trajectories.
The Macro Trajectory: A Decade of Accelerated Expansion
Our analysis establishes a clear, high-velocity growth curve for the sector. Valued at a baseline that has consistently expanded from 2020 through 2025, the global market has demonstrated remarkable resilience and accelerating momentum. The current year provides a pivotal inflection point, with total market revenue projections indicating a substantial step-up as manufacturing capacities scale and premium product adoption moves from early adopters to the mainstream.
Looking ahead, the forecast period through 2032 paints a picture of sustained, double-digit velocity. The compound annual growth rate is projected at 9.85 percent, a figure that significantly outpaces conventional dairy categories. This growth is not merely linear; it is being fueled by a convergence of nutritional advantages, demographic shifts, and strategic supply chain investments. By the close of the forecast horizon in 2032, the market is positioned to multiply substantially from its current footprint, reshaping the competitive hierarchy of the global infant nutrition sector. For stakeholders, understanding the precise drivers behind this trajectory and the timing of market inflection points is critical for capital allocation and product pipeline development.
Unpacking the Report: Operational Intelligence Beyond Headlines
While macro trends provide directional guidance, actionable strategy requires a forensic examination of the market mechanics. Our research deliverable is structured to provide immediate operational utility across multiple corporate functions. The report moves beyond aggregate figures to map the intricate ecosystem that defines value capture in this specialized segment.
Product Architecture and Formulation Dynamics
The report deconstructs the product landscape into its core commercial pillars, analyzing how different formulations command distinct price points, supply chain requirements, and consumer loyalty profiles. We examine the strategic positioning of ready-to-feed liquid sheep milk variants versus powdered formats, and critically, the dominant role that sheep milk-based infant formula plays in driving overall category valuation. The analysis dissects how manufacturers are leveraging the unique biochemical profile of sheep milk to differentiate products in a crowded marketplace, and how contract manufacturing arrangements are shaping the availability of private label and co-branded offerings in key consumer markets.
Channel Economics and Path-to-Market Strategies
Distribution is no longer a uniform function; it is a strategic battleground. Our research provides a detailed breakdown of channel performance, evaluating the economics of online retail ecosystems against traditional brick-and-mortar dominance. We analyze how specialty stores are cultivating premium brand equity, and how supermarkets and hypermarkets are adapting their shelf strategies to accommodate higher-margin sheep milk products. The report further investigates the emerging role of alternative channels and the logistical considerations that dictate channel profitability in a category where cold chain integrity and shelf-life management are paramount.
Regional Supply-Demand Asymmetries
Geographic dynamics in this market are defined by stark asymmetries between production hubs and consumption centers. The report provides a nuanced regional analysis that moves beyond simple volume tracking. It examines how production capabilities are concentrated in specific geographies with favorable agronomic conditions and established sheep farming heritage, while demand signals are emanating from diverse regional markets with varying regulatory frameworks and consumer readiness. Understanding these cross-border flows, tariff implications, and localized certification requirements is essential for any entity seeking to optimize its global footprint or enter new territories.
Competitive Landscape: The Architecture of Market Power
The sector is characterized by a competitive environment where scale, technical expertise, and supply chain control converge. Market concentration metrics indicate a moderately consolidated landscape, with the top three players commanding a significant share of total industry revenue, and the top five entities extending their influence further. This concentration reflects the high barriers to entry, including the capital intensity of milking infrastructure, the technical complexity of formulation and manufacturing, and the stringent regulatory compliance required for infant nutrition products.
Strategic Profiles of Key Market Participants
The report provides deep-dive competitive profiling of the organizations that are actively shaping the market trajectory. Our analysis highlights how leading producers are leveraging geographic advantages to secure premium raw material positioning. We examine how specialized sheep milking companies in New Zealand have established themselves as critical nodes in the global supply chain, producing both finished consumer products and bulk ingredients that feed into broader manufacturing networks. Their strategies revolve around grass-fed sourcing narratives, vertical integration from farm to formula, and the development of nutritional bases that enable other brands to formulate sheep milk products without owning upstream production assets.
Worldwide Sheep Milk and Infant Formula Market
We also analyze the strategic maneuvering of global nutrition giants that have entered the sheep milk space through targeted product launches and acquisitions. By adapting established brand architectures and leveraging distribution scale, these multinational players are testing the boundaries of sheep milk application, from toddler milk drinks to full infant formula ranges. The report evaluates their capacity to influence category standards and their approach to navigating regional formulation preferences. Additionally, the research maps the activity of regional dairy and nutrition companies operating across Europe, North America, and Asia, detailing how local market knowledge, specialized production capabilities, and targeted product portfolios are allowing them to carve out defensible positions in a globally competitive arena.
Contract Manufacturing and Ingredient Value Chains
A critical, often underappreciated layer of the competitive landscape is the role of contract manufacturing and ingredient supply. Our report dissects how several key entities are generating revenue and market influence not solely through branded consumer products, but through the provision of bulk sheep milk powders, nutritional bases, and contract production services. This B2B dimension of the market creates interdependencies and partnership opportunities that are central to understanding future M&A activity and strategic alliances. Companies that control high-quality, traceable ingredient supply are positioned to capture value across multiple branded end products, creating a multiplier effect on their strategic importance.
Regulatory and Supply Chain Fault Lines in 2026
The operational environment for sheep milk and infant formula is undergoing a period of regulatory recalibration. Recent policy developments have introduced new compliance obligations that directly impact manufacturing planning, sourcing strategies, and cross-border trade flows. Our report integrates these dynamics into a forward-looking risk assessment framework, ensuring that strategic plans are stress-tested against the evolving regulatory reality.
In late 2025, regulatory authorities in China implemented new production licensing rules that brought infant formula liquid milk under the same registration and production controls previously applied to powdered formulations. This regulatory harmonization effectively eliminated contract production pathways that were previously utilized by certain brand operators, forcing a structural shift in how liquid products are manufactured, registered, and brought to market in one of the world's most significant infant nutrition consumption regions. Simultaneously, at the beginning of 2026, European regulatory bodies reinforced import controls on specific functional ingredients used in infant formula manufacture, mandating enhanced border checks, laboratory analyses, and certification requirements. These measures introduce additional verification steps and supply chain transparency demands for manufacturers relying on imported functional oil components. The report quantifies the operational implications of these regulatory shifts and maps compliant pathway options for market entrants and established players alike.
The Premiumization Economics: Why Sheep Milk Commands Strategic Attention
The economic rationale for investing in sheep milk-based infant nutrition is rooted in a compelling nutritional narrative that translates directly into consumer preference and pricing power. Sheep milk possesses a whey-to-casein ratio that more closely aligns with human breast milk than conventional cow milk alternatives. This biochemical similarity supports digestion profiles that resonate with parents seeking gentler nutritional options for infants and toddlers, reducing tolerance issues and building brand trust. This physiological advantage is the foundational driver of product differentiation in a category where ingredient provenance and functional benefits are increasingly scrutinized by healthcare professionals and informed consumers.
However, this premium positioning is inextricably linked to supply economics. Sheep milk production incurs materially higher costs compared to conventional dairy species, driven by smaller herd sizes, lower total milk volumes per animal, and seasonal yield fluctuations. Raw sheep milk prices routinely trade at a significant premium over equivalent cow milk, creating a cost structure that demands precise inventory management, yield optimization, and premium pricing strategies to maintain margin integrity. The report provides a detailed analysis of these cost drivers, evaluating how different business models are managing the gap between input costs and realized selling prices, and identifying the operational levers that separate profitable operators from those that struggle to scale efficiently.
Strategic Recommendations for the 2026 Decision Cycle
As organizations formulate their strategic plans for the remainder of the decade, several actionable imperatives emerge from the data and competitive analysis. First, the concentration of production capabilities in a limited number of geographic regions necessitates a deliberate approach to supply chain resilience. Companies must evaluate long-term supply agreements, explore co-investment opportunities with upstream producers, and assess the risk exposure associated with reliance on single-source or concentrated ingredient flows.
Second, the regulatory environment demands proactive compliance architecture. With infant formula registration and production controls tightening in major markets, organizations must integrate regulatory strategy into product development timelines rather than treating compliance as a post-development checkpoint. The report outlines the specific registration pathways, documentation requirements, and testing protocols that will define market access in the coming years.
Third, channel strategy must be calibrated to the distinct economics of sheep milk products. Premium positioning requires distribution environments that support brand storytelling, consumer education, and controlled price maintenance. Our analysis provides a framework for evaluating channel partners, assessing shelf placement opportunities, and building omnichannel approaches that leverage online reach while preserving the premium experience in physical retail environments.
Accessing the Complete Intelligence Architecture
The analysis presented here provides a strategic overview of the market forces, competitive dynamics, and regulatory currents shaping the worldwide sheep milk and infant formula landscape. However, the full operational value of this research resides in the detailed segmentation data, regional market sizing, channel-specific revenue tracking, and granular company performance metrics that form the backbone of our comprehensive report. The precise market valuations for each product category, the channel-level revenue distributions, the regional demand allocations, and the forward-looking scenario models are essential tools for supply chain planning, pricing strategy, market entry assessments, and investor communications.
For corporate teams ready to translate this intelligence into executed strategy, the complete dataset provides the calibrated inputs required for financial modeling, capacity planning, and competitive response formulation. We invite strategic decision-makers, business development leaders, and market intelligence professionals to access the full Worldwide Sheep Milk and Infant Formula Market research to obtain the complete segmentation breakdowns, historical time-series data, five-year forecast trajectories, and detailed competitive profiling that will drive your 2026 and beyond planning cycles. The market is expanding with certainty; the organizations that succeed will be those that navigate its complexity with precision and data-driven clarity.
Goat Milk Infant Formula Market
For detailed analysis of this topic, please visit the official page: Worldwide Sheep Milk and Infant Formula Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vending Payment Market Forecast $15.2B in 2025 to $32.5B by 2032 at 11.45% CAGR
By pmarketresearch, 2026-09-16
The Contactless Imperative: Strategic Intelligence for the Worldwide Vending Machine Payment System Market (2026–2032)
The global unattended retail ecosystem is undergoing a structural transformation. What was once a convenience-driven upgrade has become a fundamental infrastructure requirement. As consumer expectations shift toward frictionless, hygienic, and instantaneous transactions, vending machine payment systems have evolved from peripheral hardware into the central nervous system of modern self-service commerce. Our newly published Worldwide Vending Machine Payment System Market research study provides enterprise leaders, hardware manufacturers, payment processors, and vending operators with the analytical rigor required to navigate this inflection point through 2032.
This article outlines the strategic architecture of the study, emphasizing why 2026 represents a critical decision window for capital allocation, technology roadmapping, and competitive positioning. While we highlight the macro trajectory, regulatory pressures, and competitive dynamics shaping the sector, the granular segmentation data, regional revenue breakdowns, and proprietary operator benchmarks are reserved for the full report. Leadership teams that require precise investment thresholds, channel profitability modeling, and deployment sequencing frameworks will find the complete study essential.
Macro Trajectory: Why 2026 Is a Defining Baseline Year
The market has demonstrated sustained momentum across the historical evaluation window (2020–2025), with operational scale expanding rapidly as cashless acceptance moved from early adoption to mainstream standard. The industry closed the base year of 2025 at approximately 15,214.5 million USD , reflecting a decisive pivot away from cash-reliant architectures. Our forward projections map a clear uptrend through 2032, with the market expected to surpass 32,500 million USD by the end of the forecast horizon. The implied compound annual growth rate of 11.45% signals more than incremental expansion; it indicates a sector-wide restructuring of how payment infrastructure is designed, integrated, and monetized.
Several structural drivers underpin this trajectory. First, the installed base of connected vending endpoints has crossed a critical threshold, with industry monitoring reporting over 8.1 million connected vending machines globally in 2025 . Second, consumer behavior has stabilized around contactless preferences, with operator-side data indicating that 71% of vending transactions were cashless in 2024 , and roughly 77% of those cashless transactions were executed via tap or contactless methods . Speed, hygiene, and ease of use are no longer differentiators; they are baseline purchase conditions. Third, telemetry-enabled payment terminals are transforming vending from a transactional channel into a data-rich operational environment, enabling dynamic pricing, real-time inventory visibility, and predictive maintenance workflows that can reduce machine downtime by up to 30% for operators deploying IoT-enabled cashless solutions.
For decision-makers, these trends create a clear strategic implication: payment system selection is now inseparable from operational efficiency, data capture, and customer experience strategy. Companies that treat payment hardware as a commodity procurement item risk underutilizing one of the most valuable data and engagement layers in unattended retail.
Market Architecture: Payment Modalities, End-Use Verticals, and Regional Realities
The growth narrative is not monolithic. It is shaped by the interplay between payment technology maturity, vertical-specific deployment requirements, and regional regulatory environments. Our research dissects these layers to help organizations identify where adoption is accelerating, where integration complexity is highest, and where value capture will be concentrated.
Payment Technology Shifts
The market is increasingly defined by the dominance of contactless and mobile wallet acceptance, supported by card-based readers and emerging digital currency or QR-based pathways. Contactless NFC and mobile wallet integration now commands the largest share of payment system activity, reflecting the consumer preference for tap-and-go transactions and the operational advantage of reduced transaction friction. Credit and debit card readers continue to serve as a foundational layer, particularly in markets where mobile wallet penetration or infrastructure readiness varies. QR code and digital currency solutions represent a smaller but strategically important segment, especially in regions where smartphone-based payment ecosystems are advancing rapidly or where legacy hardware modernization requires low-cost bridging solutions.
End-Use Vertical Deployment Patterns
Vending machine payment systems are deployed across a diverse set of environments, each with distinct throughput expectations, security requirements, and integration constraints. Retail and commercial locations represent a major demand center, driven by high foot traffic and the need for fast, reliable payment acceptance in convenience-oriented settings. Transportation hubs form another critical axis, where unattended retail must accommodate transient passenger flows, higher transaction volumes, and stringent uptime expectations. Offices and institutions contribute steady, recurring demand tied to employee convenience, campus services, and controlled-access environments. Healthcare facilities introduce additional considerations around accessibility, hygiene, and compliance-sensitive deployment settings. Each vertical requires a different balance of hardware durability, telemetry capability, payment method breadth, and service-level commitments.
Regional Divergence and Strategic Implications
Regional dynamics shape both demand volume and technology preference. North America continues to reflect a mature, highly penetrated unattended retail market with strong emphasis on integrated telemetry and analytics. Asia Pacific captures substantial momentum, supported by rapid mobile payment ecosystem development, expanding urban convenience channels, and aggressive modernization of legacy machine fleets. Europe maintains a robust footprint shaped by regulatory nuance, particularly around contactless exemptions for unattended terminals and data security expectations. Latin America and the Middle East and Africa represent growth territories where infrastructure development, currency dynamics, andOperator adoption cycles create distinct entry and expansion strategies. The full study maps these regional trajectories in greater detail, enabling firms to align go-to-market timing, partner selection, and pricing architecture with local realities rather than global averages.
Competitive Landscape: Differentiation in a Consolidating Ecosystem
Strategic planning in this market requires a clear understanding of how incumbents and specialists are positioning themselves. The sector is characterized by a moderate concentration profile, with the top three players accounting for roughly 42.5% of market activity and the top five reaching approximately 58.2% . This structure suggests that scale matters, but differentiation remains achievable through software integration, telemetry capabilities, vertical specialization, and global service coverage.
Nayax Ltd. , headquartered in Herzliya, Israel, has built a global footprint around cashless vending payment systems that combine credit card readers, contactless and NFC terminals, mobile wallet integration, and telemetry for operators and manufacturers. Its end-to-end ecosystem positioning was reinforced through recent trade show showcases emphasizing cashless acceptance, real-time analytics, and loyalty program integration. Cantaloupe, Inc. , based in Malvern, PA, USA, competes through ePort and related cashless payment devices, vending management software, and connected solutions for vending, micro-markets, and unattended retail, with a strong emphasis on real-time analytics and operational visibility. Recent industry reporting also highlighted Cantaloupe's significant installed base and its leadership in documenting cashless and contactless transaction trends.
Worldwide Vending Machine Payment System Market
Crane Payment Innovations (CPI) , operating in the USA as part of Crane Co., remains a leading provider of cashless payment systems, card readers, and telemetry, including mobile wallet solutions and integration pathways for existing hardware. Azkoyen Group , including Coges, based in Navarre, Spain, develops payment systems, coin mechanisms, and telemetry solutions integrated into vending machines, offering cashless and connected offerings for global operators. European and global specialists further expand the competitive field: Vendon , headquartered in Estonia, focuses on cashless payment terminals, telemetry, and IoT solutions that enable remote monitoring and mobile payments; Televend (INTIS) , with global operations centered in Europe, provides T-Pay cashless devices and T36 telemetry hardware aimed at modernizing legacy machines with real-time data, AI-enabled tools, and dynamic pricing capabilities; and Ingenico , based in France with global reach, supplies adaptable payment terminals and unattended payment systems including contactless solutions suited to vending environments.
Additional players extend the ecosystem into specialized niches. 365 Retail Markets , based in the USA, delivers PayPlus card readers and cashless solutions integrated with micro-markets and vending, supporting credit, debit, and mobile wallets. Heartland (Global Payments) , USA-based, provides secure cashless payment systems and card readers tailored for unattended vending, laundromats, and similar self-service environments. Apriva , also USA-based, delivers self-service payment processing, devices, and connectivity platforms that extend beyond vending into EV charging and unattended retail. HID Global , with US headquarters and global operations, supplies RFID and contactless payment readers and modules for integration into vending machines and kiosks, supporting cashless and credential-based transactions. Gantner , based in Austria, offers RFID/NFC cashless payment terminals designed for snack and drink vending, enabling membership or employee card payment models.
This competitive mosaic matters because procurement decisions are increasingly evaluated on total operational value rather than terminal price alone. Operators and OEMs weigh telemetry integration, analytics readiness, remote management capabilities, compliance support, and ecosystem compatibility. The full report provides detailed company profiling, strategic positioning analysis, and recent development tracking to support competitive benchmarking and partner selection.
Regulatory, Security, and Operational Dynamics
Payment system strategy cannot be separated from compliance and risk management. As vending machines handle cardholder data, they must align with PCI DSS requirements for secure storage, processing, and transmission of payment information. Shared responsibility models become especially relevant when machines are operated by third parties, making contractual clarity and technical architecture decisions central to risk exposure. Industry analyses suggest that PCI DSS compliance costs for larger organizations can range from 50,000 to 200,000+ USD annually when audits and related controls are included, while smaller entities using self-assessment questionnaires may face annual costs in the 5,000 to 20,000 USD range. Non-compliance penalties can escalate quickly, with reported potential penalties reaching 100,000 USD per month in certain circumstances. These financial and operational stakes make compliance-ready design a strategic priority rather than a backend checkbox.
In parallel, regional regulatory nuances are shaping transaction flow design. Contactless payments at vending machines often qualify for exemptions from Strong Customer Authentication under EU regulations for low-value or unattended terminals, enabling faster tap-and-go transactions without PIN entry. This exemption supports the broader consumer demand for speed and convenience, while also influencing terminal configuration, transaction routing, and regional deployment strategies. The interplay between regulation, user experience, and fraud-risk management is a recurring theme in the study, particularly for firms operating across multiple jurisdictions.
Strategic Value for 2026 Decision-Making
The 2026–2032 forecast window is not merely a planning horizon; it is a period in which legacy modernization, contactless standardization, telemetry adoption, and compliance readiness will separate scalable operators from those burdened by fragmented systems and manual workflows. Our research is designed to support several high-value decision contexts:
- Capital allocation and fleet modernization planning: Understanding where connected payment systems deliver the strongest operational return, including downtime reduction, remote monitoring, and predictive maintenance benefits.
- Payment technology roadmap prioritization: Evaluating the balance between contactless NFC and mobile wallet readiness, card reader continuity, and emerging QR or digital currency pathways based on vertical and regional fit.
- Competitive positioning and partnership strategy: Mapping incumbent capabilities, installed base dynamics, and ecosystem differentiation to inform supplier selection, OEM integration, and service partnership decisions.
- Compliance and risk architecture: Incorporating PCI DSS considerations, shared responsibility structures, and regional authentication rules into terminal selection and deployment planning.
- Market entry and expansion sequencing: Aligning regional demand signals, vertical adoption patterns, and infrastructure readiness with realistic growth pathways rather than aggregated global assumptions.
The study integrates historical performance, forward projections, segmentation analysis, company profiling, and regulatory context into a single decision-support framework. Importantly, it avoids treating the market as a single average growth curve. Instead, it isolates where value is being created, which payment modalities are gaining traction, and how operators and manufacturers are translating technology adoption into measurable efficiency and revenue gains.
What the Full Study Delivers
Beyond the macro trajectory and competitive context summarized here, the complete Worldwide Vending Machine Payment System Market report provides operational depth designed for strategy, finance, product, and sales leadership. The analysis covers market sizing and forecast architecture across the 2020–2032 window, payment-type dynamics, end-use vertical deployment characteristics, and regional demand patterns. It also includes company profiles, recent development tracking, and concentration analysis to support competitive intelligence and partnership evaluation.
The report is structured to translate market movement into actionable insight. For vending operators, it supports fleet upgrade timing, payment method mix decisions, and telemetry investment priorities. For payment system suppliers and OEMs, it clarifies integration opportunities, vertical-specific requirements, and differentiation levers in a consolidating landscape. For investors and strategic planners, it provides a structured view of growth drivers, compliance overhead, and competitive density.
Transportation Ticket Vending Machine (TVM) Market
Conclusion: From Contactless Adoption to Strategic Advantage
The Worldwide Vending Machine Payment System Market is moving from rapid adoption to refined differentiation. Contactless and mobile wallet acceptance have become the operational norm, telemetry has turned payment terminals into management platforms, and regulatory frameworks have elevated compliance from a technical requirement to a strategic design constraint. In this environment, the organizations that outperform will be those that treat payment infrastructure as an integrated capability spanning hardware, software, data, security, and customer experience.
This research study is intended to give leadership teams the clarity required to act with confidence in 2026 and beyond. The headline trajectory, competitive dynamics, and operational pressures are visible here; the detailed segmentation breakdowns, regional revenue contours, end-use profitability context, and proprietary benchmarking are developed fully in the report itself. For executives responsible for unattended retail strategy, payment ecosystem planning, or vending fleet modernization, the complete study provides the granularity needed to convert market momentum into disciplined, high-conviction decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Vending Machine Payment System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Light Guides Market to Reach $4,521.81M by 2032 at 8.42% CAGR
By pmarketresearch, 2026-09-16
Lighting the Path Forward: Strategic Intelligence for the Global Light Guides Market 2026–2032
The worldwide light guides market stands at a critical inflection point. Driven by rapid advancements in display technologies, automotive lighting architectures, and precision medical instrumentation, optical transmission components have evolved from passive hardware elements into strategic enablers of product differentiation and performance optimization. For executives navigating capital allocation, supply chain redesign, and product roadmap planning in 2026, the market presents both high-opportunity growth corridors and complex structural shifts that demand granular, actionable intelligence. Our newly released Worldwide Light Guides Market research report delivers the comprehensive analytical framework required to turn these dynamics into informed corporate strategy.
Drawing on a five-year historical baseline and a seven-year forward projection, this study maps revenue trajectories, material substitution patterns, competitive repositioning, and regional manufacturing realignments that will shape procurement, engineering, and market entry decisions throughout the decade. Rather than offering surface-level aggregates, the report is engineered to support cross-functional decision-making across R&D, operations, sourcing, and corporate strategy.
Macro Trajectory and Structural Growth Signals
The market has demonstrated consistent expansion over the past half-decade, with revenue scaling from a baseline of approximately $1.72 billion in 2020 to an estimated $2.57 billion by 2025. This historical momentum establishes a credible platform for the forecast period, during which the market is projected to reach $2.85 billion in 2026 and continue climbing toward $4.52 billion by 2032. The implied compound annual growth rate of 8.42 percent reflects sustained demand pull across multiple end-use verticals, compounding the effects of technological upgrades and capacity additions already underway.
Several interconnected forces underpin this trajectory. Edge-lit illumination architectures continue to benefit from miniaturization requirements in consumer-facing devices, while automotive OEMs push toward adaptive interior and exterior lighting that relies on high-efficiency light guide plates and molded optical components. At the same time, industrial and medical applications are expanding their reliance on specialty light guides for precision illumination, spectroscopy, and minimally invasive instrumentation. These demand drivers are reinforcing volume growth while simultaneously elevating performance thresholds around uniformity, thermal tolerance, and wavelength-specific transmission.
Linear Guide Market
The forward outlook is further shaped by material dynamics that directly influence manufacturing economics and sourcing strategies. Optical-grade acrylic (PMMA) remains the dominant material foundation for light guide plates due to its combination of clarity and cost efficiency, while polycarbonate maintains a meaningful position where heat resistance and impact durability are non-negotiable. Recent analyst observations highlight that polycarbonate pricing in Asia exhibited relative stability through late 2025, with early-2026 FOB benchmarks around $1,876 per metric ton in China and $1,622 per metric ton in India. Meanwhile, PMMA raw material pricing experienced notable volatility across a twelve-month window, creating planning complexity for producers dependent on predictable input costs. These price behaviors are not abstract macroeconomic footnotes; they are direct inputs to margin modeling, vendor negotiations, and inventory strategy.
At the same time, the display sector introduces a structural substitution dynamic that warrants close monitoring. Broader adoption of OLED technologies in premium devices has begun to reduce demand for certain light guide plate applications, while a meaningful share of high-performance laptops has shifted toward OLED alternatives. This transition does not negate the light guides opportunity; rather, it sharpens the focus on where light guides retain a decisive cost, performance, or design advantage, including edge-lit backlighting, signage, and specific automotive interior configurations. Understanding the precise boundaries of substitution is essential for accurate volume forecasting and product portfolio planning.
Competitive Landscape: Scale, Focus, and Strategic Reinvestment
The market exhibits moderate concentration, with the top three participants accounting for a combined share of approximately 34.28 percent and the top five exceeding 51.92 percent. This structure indicates a landscape where established manufacturers hold meaningful scale advantages in mainstream optical components, while specialized and regional players compete on customization, rapid prototyping, and application-specific engineering. For procurement teams and strategy leaders, this implies a bifurcated vendor ecosystem in which commodity segments increasingly reward scale and integration, whereas high-performance segments reward technical collaboration and process capability.
Worldwide Light Guides Market
Leading incumbents are actively reinforcing their competitive positions through targeted investments. SCHOTT AG continues to advance flexible glass optical fiber light guides, bundles, cables, and assemblies tailored for medical, industrial, and electronics applications. The company's PURAVIS® fiber platform emphasizes high transmission and customization to nanometer tolerances, and its recent production expansion includes bioburden-controlled ISO 7/8 cleanroom services in Mexico to support complex light guide assemblies for medical use. Lightguide International is strengthening its specialty optical fiber and laser delivery capabilities, expanding optical fiber production lab capacity to support scientific, industrial, and medical applications across a span of continents, with full custom development from prototype through mass production. Global Lighting Technologies remains positioned around custom molded LED-based edge-lit light guides and light guide plates, leveraging advanced micro-optical extraction methods for uniform illumination across consumer electronics, automotive, and general lighting applications, with multiple manufacturing facilities in Asia and additional capacity in Vietnam.
Parallel activity among regional and application-focused suppliers adds important texture to the competitive map. Astra Products supports edge-lit displays and backlighting through CLAREX acrylic light guide panels, light guide reflectors, and high scatter optical transmission light guides, complemented by custom printing and finishing options. Yongtek manufactures light guide plates from acrylic and polystyrene using extrusion, silk printing, and laser methods for LED lighting, displays, automotive interiors, and signage. Thorlabs contributes to the scientific and laboratory segment with liquid light guides designed for broad wavelength transmission, while RSP, Inc. supplies custom light guide films for LED backlighting in compact consumer products. Nanjing Giant Technology rounds out the competitive field with plastic and glass optical fiber light guides, including ring light guides and custom bundles for non-communication illumination uses.
Strategic developments in late 2025 reinforce the theme of deliberate capability expansion and product repositioning. HOYA Corporation signaled a move toward targeting light guides for AR glasses as a next step following its camera lens focus, illustrating how optical specialists are extending core competencies into near-eye display architectures. Global Lighting Technology's detailed guidance on custom optical pattern application methods for acrylic and polycarbonate light guide plates, including micro-machined mirror-finished structures, underscores the ongoing engineering emphasis on illumination uniformity and structural precision. Taken together, these moves suggest that competition is increasingly defined by process control, application integration, and geographic diversification.
Regulatory Friction and Supply Chain Reconfiguration
The operating environment is being reshaped as much by policy and trade dynamics as by technology roadmaps. U.S. tariffs imposed in early 2025 on imported components from major manufacturing hubs have prompted a broad reassessment of sourcing strategies and accelerated exploration of near-shoring alternatives for light guide plates, particularly within the automotive sector. For global manufacturers, this creates a dual challenge: maintaining cost competitiveness while building or qualifying supply options that reduce exposure to border friction and currency volatility. The result is a market in which geographic diversification, supplier redundancy, and regional manufacturing footprints are becoming strategic imperatives rather than optional contingency measures.
These trade-driven pressures intersect with material sourcing considerations. As regional price behavior diverges and production capacity is rebalanced, firms that rely on single-source input dependencies or concentrated manufacturing locations face elevated risk. The report examines how these dynamics affect lead times, qualification cycles, and total cost of ownership, providing executives with the analytical scaffolding to evaluate make-versus-buy decisions, dual-sourcing structures, and regional capacity investments with greater precision.
Inside the Worldwide Light Guides Market Research Report
This research is designed to translate market complexity into decision-ready intelligence. The study opens with comprehensive market sizing and forecast modeling that links historical performance to forward projections, allowing leadership to benchmark current performance against top-down opportunity ranges and scenario-based growth paths. Segmentation analysis dissects demand across material types and application domains, revealing where optical performance requirements, cost sensitivities, and substitution risks converge. Regional evaluations provide a structured comparison of demand intensity, manufacturing presence, and trade exposure, helping teams prioritize market entry, expansion, or sourcing shifts with confidence.
Beyond sizing, the report delivers practical operability through several integrated sections. A competitive profiling module maps the strategic positioning, capability strengths, and recent investments of leading participants, enabling benchmarking against internal development roadmaps and supplier evaluation criteria. A raw material and cost dynamics section contextualizes input pricing behavior, substitution economics, and planning implications for producers and buyers alike. A regulatory and trade impact analysis identifies policy-driven risks and near-shoring incentives that may influence procurement strategy, capacity placement, and contract structures over the forecast horizon.
The report also integrates recent corporate developments to illustrate how strategic intent is translating into tangible capability changes. Whether it is cleanroom expansion for medical assemblies, production lab capacity increases for specialty fiber systems, or product-level enhancements in micro-optical patterning, these developments are interpreted within a broader framework of competitive advantage and supply reliability. This approach ensures that executives do not merely observe industry events, but understand their implications for sourcing resilience, technology readiness, and time-to-market.
Why This Research Matters for 2026 Decision-Making
In a market growing at a sustained mid-to-high single-digit compound rate, strategic advantage accrues to organizations that can couple demand visibility with operational agility. The light guides sector is not defined by a single dominant application or material; rather, it is shaped by overlapping transitions in display formats, automotive lighting requirements, medical device sophistication, and regional manufacturing economics. Decision-makers must therefore answer a set of interrelated questions: where does growth concentrate by application and geography, which material substitutions will persist versus plateau, how should sourcing portfolios be restructured in response to trade policy, and which competitors are most likely to shape pricing and capacity dynamics in each segment.
This report is built to help leadership teams answer those questions with rigor. It provides the analytical foundation to align R&D roadmaps with realistic substitution boundaries, to inform procurement strategies that balance cost efficiency with supply resilience, and to evaluate potential partnerships, acquisitions, or capacity investments against credible market trajectories. The study's forecast architecture, segmentation logic, and competitive mapping are intended to support scenario planning, allowing organizations to test assumptions around demand sensitivity, input cost volatility, and regulatory exposure before committing capital or redesigning product architectures.
For executives seeking to move beyond intuition and into structured strategic planning, the essential next step is access to the full analytical detail that underpins these conclusions. The complete Worldwide Light Guides Market research report presents the internal data tables, segment breakdowns, regional comparisons, and competitive profiles necessary to operationalize the insights summarized here. We invite you to explore the full report to obtain the granular intelligence required to align your organization's next planning cycle with the market's most consequential developments.
For detailed analysis of this topic, please visit the official page: Worldwide Light Guides Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Industrial High Res Camera Market Hits $1.54B in 2025, Projects 8.28% CAGR to 2032
By pmarketresearch, 2026-09-16
Worldwide Industrial High Resolution Camera Market: Strategic Intelligence for 2026 Decision-Making
The industrial imaging landscape is undergoing a structural transformation. As manufacturing systems grow more digitized, inspection requirements become more stringent, and automation architectures demand higher fidelity data capture, high resolution cameras have moved from peripheral components to critical enabling technologies. PW Consulting’s latest Worldwide Industrial High Resolution Camera Market study provides a comprehensive, forward-looking assessment of this rapidly evolving sector, designed specifically to equip leadership teams with the analytical rigor required for confident 2026 strategic planning.
This research does not merely catalog historical performance. It constructs a decision-ready framework that maps revenue trajectories, competitive positioning, technological inflection points, and supply chain pressures across a forecast horizon extending through 2032. The following overview illustrates the depth and operational utility embedded within the full report, while preserving the precise segmentation data, regional breakdowns, and proprietary modeling outputs that subscribers will access in the complete intelligence package.
Macro Trajectory and Revenue Architecture
The global industrial high resolution camera market has demonstrated consistent expansion across the historical review period, with total revenue climbing from approximately 1,045 million USD in 2020 to an estimated 1,540 million USD in 2025. This growth reflects sustained capital investment in automated visual inspection, precision metrology, and advanced manufacturing platforms that require imaging systems capable of resolving fine structural details at production-line speeds.
Looking ahead, the market is projected to advance to 1,715 million USD in 2026 and continue its upward trajectory toward 2,687 million USD by 2032. The forecast period compound annual growth rate of 8.28 percent underscores a sector that is expanding faster than many adjacent industrial automation categories. This rate is not uniform across all vectors; rather, it is shaped by divergent adoption curves, regional industrial policy shifts, sensor technology transitions, and the pace at which end-use sectors integrate higher-resolution imaging into routine quality and process control workflows.
Several structural forces explain this momentum:
- Increasing defect-detection sensitivity requirements in electronics and semiconductor fabrication, where sub-pixel feature resolution directly correlates with yield improvement and waste reduction.
- The migration from legacy CCD architectures toward high-performance CMOS platforms, driven by improvements in quantum efficiency, read noise reduction, power efficiency, and integration flexibility.
- Expanding deployment of high-speed line-scan and area-scan configurations in continuous-motion manufacturing environments, where frame-rate and resolution must scale together without compromising throughput.
- Growing integration of vision subsystems into broader automation ecosystems, including robotic guidance, volumetric measurement, and inline metrology stations that depend on deterministic image acquisition.
The full study dissects these drivers through multi-axis modeling that isolates the contribution of each segment while maintaining a cohesive view of total market momentum. Decision-makers will find that the aggregate figures tell only part of the story; the actionable intelligence lies in understanding which technology pathways, application domains, and geographic clusters are accelerating, which are plateauing, and why.
Competitive Landscape: Positioning Among Established and Emerging Players
The competitive architecture of the industrial high resolution camera market is characterized by a blend of specialized imaging manufacturers, diversified machine vision conglomerates, and regional suppliers leveraging localized manufacturing and distribution advantages. The report provides detailed company profiles, capability mapping, and strategic assessment for the leading organizations shaping the market’s direction.
European suppliers maintain a strong presence through product breadth and application engineering depth. Basler AG offers a wide portfolio of industrial high-resolution area-scan and line-scan cameras with CMOS sensors reaching up to 65 megapixels, supported by GigE, USB3, and CoaXPress interfaces for machine vision, factory automation, and inspection applications. Allied Vision Technologies specializes in high-resolution 2D, 3D, and SWIR cameras for industrial automation, semiconductor inspection, and medical imaging, with an emphasis on smart vision systems and high-performance CMOS sensors. JAI A/S focuses on multi-sensor and high-resolution industrial cameras, including prism-based color models, for machine vision, automation, and surface inspection applications. Baumer manufactures high-performance CMOS industrial cameras with resolutions up to 65 megapixels, supporting GigE Vision, USB3 Vision, and Camera Link for precision measurement and automation.
North American firms contribute significant innovation in ultra-high-speed and high-resolution architectures. Teledyne DALSA provides high-resolution machine vision cameras, including area-scan and line-scan models with advanced CMOS sensors for electronics, semiconductor, and industrial inspection. Emergent Vision Technologies develops ultra-high-speed, high-resolution cameras reaching more than 100 megapixels with 10GigE, 25GigE, and 100GigE interfaces, including Zenith series models for industrial automation and volumetric imaging. Lucid Vision Labs offers Triton and Phoenix series GigE and high-resolution machine vision cameras with IP67-rated options for industrial environments and OEM integration. Adimec specializes in high-resolution cameras optimized for metrology, semiconductor wafer inspection, and electronics inspection with active sensor control features. Vision Systems Technology supplies ultra-high-resolution cameras leveraging advanced CMOS sensors for precision industrial imaging and inspection. Cognex Corporation develops smart machine vision cameras and systems with high-resolution capabilities for industrial inspection and quality control.
Asia-Pacific participants are increasingly influential in expanding price-performance options and scaling supply capacity. Daheng Imaging provides industrial cameras, optical systems, and high-resolution imaging solutions for automation and machine vision applications. Huaray Tech manufactures high-speed and high-resolution industrial cameras for various automation and imaging applications. Omron Corporation integrates high-resolution vision systems and cameras into automation solutions for industrial manufacturing and inspection.
The report evaluates each company across multiple strategic dimensions: sensor integration capability, interface roadmap alignment, application-specific validation, OEM partnership models, and capacity to manage supply chain volatility. This competitive profiling enables clients to benchmark their own product strategy, identify partnership or acquisition targets, and anticipate market share shifts as technology and regional cost structures evolve.
Recent Product and Technology Developments Shaping 2026 Investment
Innovation velocity in this sector has accelerated markedly over the past twelve to eighteen months. The study incorporates a structured review of recent launches and component-level advances that are reshaping performance ceilings and integration economics.
Worldwide Industrial High Resolution Camera Market
In September 2025, Emergent Vision Technologies released five new models in the ZENITH 100GigE camera series based on Sony Pregius S sensors, offering up to 105 megapixel resolution and frame rates exceeding 800 fps for industrial automation applications. This launch illustrates the ongoing convergence of extreme resolution and extreme data throughput, raising the bar for infrastructure planning in high-speed inspection environments.
STMicroelectronics advanced its sensor portfolio in October 2025 with four new 5-megapixel CMOS image sensors in the ST BrightSense family, featuring hybrid global and rolling shutter modes for industrial automation, machine vision, and robotic applications, with mass production scheduled for February 2026. Such component-level releases influence downstream camera design cycles, cost structures, and the timing of new product introductions across multiple manufacturers.
AT Sensors launched the C7 triangulation camera series for high-speed industrial 3D scanning in March 2026, delivering up to five times higher data throughput with 3072 pixels per profile for inline inspection tasks. This development highlights the growing demand for high-resolution 3D profiling that can operate within tight cycle-time constraints.
SinceVision Technology announced its 2026 lineup in December 2025, including high-speed cameras up to 5K and 21-megapixel resolution alongside 3D laser profilers for high-precision industrial inspection in smart manufacturing. These successive product announcements indicate that suppliers are not only competing on resolution alone but also on the integration of speed, robustness, and application-tuned optical performance.
The full report situates these developments within a broader technology roadmap, enabling clients to distinguish between incremental specification improvements and step-change innovations that could alter procurement strategies, system architecture choices, or competitive differentiation timelines.
Supply Chain Pressures and Regulatory Dynamics
Strategic planning for 2026 cannot ignore the operational realities affecting sensor procurement, component pricing, and cross-border trade. The research integrates recent industry intelligence on cost and availability pressures that are directly influencing manufacturing schedules and margin management across the industrial camera sector.
U.S. imposition of tariffs on imported semiconductors and related components has increased production costs for machine vision systems by an estimated 8 to 12 percent in affected supply chains. This cost pressure is not uniformly distributed; it varies by sourcing strategy, bill-of-materials composition, and the extent to which manufacturers can reallocate procurement or adjust assembly locations.
Semiconductor shortages and extended component lead times for CMOS image sensors have constrained production schedules for industrial camera manufacturers. Even as certain bottlenecks ease, the timing and reliability of sensor availability remains a critical variable for companies planning product launches, capacity expansion, and customer commitments.
In parallel, rising costs of silicon wafers and specialized materials for CMOS sensor fabrication continue to pressure manufacturing expenses in the industrial camera sector. These input-cost dynamics affect not only sensor pricing but also the broader economics of upstream fabrication, which can cascade into lead-time variability and negotiation leverage for downstream camera builders.
Regulatory complexity adds another layer of strategic risk. U.S. export controls on advanced computing commodities to China include case-by-case licensing for certain AI-related chips below specific performance thresholds, impacting broader electronics and imaging supply chains. While the direct scope of these controls varies, their presence alters planning assumptions for manufacturers with cross-border component flows, distribution networks, or end-market exposure. The complete report analyzes how these regulatory and supply chain factors interact with regional demand patterns and competitive sourcing options.
Application Landscape and Technology Transition
The industrial high resolution camera market serves a diverse set of end-use domains, each with distinct performance requirements, inspection tolerances, and adoption cycles. Semiconductor and electronics manufacturing continues to be a major demand center, where high spatial resolution and stable repeatability support wafer-level inspection, component verification, and advanced packaging quality control. Automotive manufacturing relies on high-resolution imaging for surface defect detection, assembly verification, and increasingly for guided processes that depend on precise visual feedback. Pharmaceuticals and medical applications demand imaging systems capable of supporting stringent documentation, cleanliness, and metrology expectations. Logistics and packaging operations utilize high-resolution cameras for label reading, code verification, dimensioning, and automated sorting where throughput and reliability must remain balanced. Additional application areas extend into surface inspection, robotics integration, and specialized metrology tasks that require tailored optical configurations.
Across these domains, the transition toward CMOS-based sensors is a defining strategic theme. CMOS architectures are increasingly favored for their improved integration potential, lower power consumption, and expanding performance envelope that continues to narrow the gap with traditional CCD solutions in many industrial scenarios. Nevertheless, the report emphasizes that sensor selection is not a simple binary decision. The appropriate imaging architecture depends on resolution targets, exposure conditions, frame-rate requirements, noise tolerance, interface constraints, and total system cost. The study provides a structured evaluation of these trade-offs so that engineering and procurement teams can align technology choices with application realities rather than specification-marketing alone.
Regional Dynamics and Strategic Sourcing Considerations
Regional market structure plays a decisive role in how industrial high resolution camera demand evolves, how competition is organized, and how supply chain risk is managed. Manufacturing density, automation investment cycles, local content expectations, and trade policy all influence the geography of opportunity. The report examines regional demand patterns and supplier distribution without reducing the analysis to static share percentages, because the strategic value lies in understanding momentum, dependency, and transition points rather than snapshot figures alone.
In regions with intensive electronics and semiconductor manufacturing, demand is closely tied to fab expansion, packaging complexity, and inspection automation programs. In automotive and heavy manufacturing centers, adoption is shaped by line modernization schedules, quality-program mandates, and the availability of skilled integration partners. In healthcare and pharmaceutical environments, procurement is influenced by compliance requirements, validation cycles, and the need for imaging solutions that can operate reliably within tightly controlled processes. Across all regions, the interplay between local suppliers and globally active manufacturers affects pricing, customization depth, support responsiveness, and supply continuity.
The full study provides a decision-oriented regional analysis that helps clients evaluate where to prioritize sales efforts, how to structure distribution partnerships, and which sourcing strategies best balance cost, performance, and risk in an environment where trade policy and component availability can shift material outcomes within a single planning cycle.
How This Study Supports 2026 Decision-Making
PW Consulting’s Worldwide Industrial High Resolution Camera Market research is built for executive, product, sales, and supply chain teams that need more than high-level trend commentary. The report is structured to support concrete decisions in several areas:
- Portfolio planning: Identify which resolution tiers, sensor technologies, and interface configurations are gaining adoption momentum and which are facing substitution or saturation risk.
- Competitive positioning: Assess how major players differentiate through resolution ceilings, speed performance, environmental robustness, OEM integration support, and application-specific validation.
- Sourcing and supply continuity: Incorporate sensor availability, input-cost trends, tariff exposure, and export-control considerations into procurement and manufacturing plans.
- Market entry and expansion: Evaluate regional demand intensity, application mix, and competitive thickness to prioritize investment and partnership strategies.
- Product roadmap alignment: Use recent product launches and sensor-component advances to anticipate customer expectations and infrastructure requirements for next-generation systems.
Each section of the report is designed to link market evidence to operational consequences. Rather than presenting the market as a single growth narrative, the analysis isolates the segments, technologies, and competitive dynamics that will determine which companies capture share efficiently and which face margin compression, capacity constraints, or misalignment with end-user requirements.
What the Full Report Delivers
The complete Worldwide Industrial High Resolution Camera Market study provides a unified analytical structure that combines historical performance review, forecast modeling, segmentation analysis, competitive profiling, technology assessment, and supply chain context. Subscribers gain access to detailed company evaluations, structured recent-developments tracking, and decision frameworks that translate market signals into planning actions. The research is intended to support scenario testing, investment prioritization, product strategy refinement, and competitive benchmarking across the 2026 to 2032 horizon.
Access the Complete Strategic Intelligence
This overview has highlighted the scope, methodological rigor, and decision-relevant content embedded in the full study. To obtain the complete segmentation intelligence, regional analysis, company benchmarking, and forecast detail required for precise 2026 planning, access the full PW Consulting report through our official market research portal. The complete package is structured for immediate use by strategy, R&D, procurement, and commercial leadership teams seeking a reliable foundation for industrial high resolution camera market decisions.
Industrial Cameras Market
For detailed analysis of this topic, please visit the official page: Worldwide Industrial High Resolution Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
BaBr2 Market Reaches $47.6M in 2025, Projects 4.3% CAGR to $63.91M by 2032: PW Consulting
By pmarketresearch, 2026-09-16
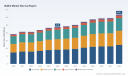
Strategic Intelligence in the BaBr2 Market: Navigating Growth and Volatility Through 2032
The global Barium Bromide (BaBr2) market stands at a critical inflection point, shaped by evolving industrial applications, raw material dynamics, and tightening regulatory frameworks. For executives, procurement leaders, and R&D directors operating in specialty chemicals, advanced materials, and imaging technologies, timely and granular market intelligence is no longer optional. PW Consulting's latest BaBr2 Market Research report delivers a comprehensive, data-driven foundation for strategic planning across the 2026-2032 horizon.
This analysis synthesizes historical performance, forward-looking projections, and structural market shifts to equip decision-makers with actionable clarity. Rather than presenting static figures, the report is engineered to support scenario modeling, supply chain optimization, and competitive positioning in a market characterized by moderate but consistent growth, regional imbalances, and concentration-driven pricing dynamics.
Market Trajectory and Macro Performance
The BaBr2 market has demonstrated resilient expansion over the past half-decade, reflecting steady demand from advanced materials, optical manufacturing, and specialized chemical synthesis. Based on our baseline assessments, global revenue reached approximately 47.6 million USD in the base year of 2025, building on a trajectory that traced 38.5 million USD in 2020, 41.5 million USD in 2021, 41.4 million USD in 2022, 43.8 million USD in 2023, and 46.6 million USD in 2024. The slight normalization observed in 2022 gave way to renewed momentum as downstream industrial activity accelerated and high-purity grades gained broader adoption.
Looking ahead, our forecast models project steady annual valuation gains, with the market expected to reach approximately 63.9 million USD by 2032. This translates to a compound annual growth rate (CAGR) of 4.3 percent over the forecast window. While the growth rate may appear measured, it conceals significant variation across applications and regional demand centers, as well as pockets of elevated premium pricing for high-purity or certified grades. Strategic planners should therefore interpret headline growth figures as a baseline rather than a substitute for segment-level and supply-side analysis.
Segmentation Architecture and Demand Drivers
The BaBr2 value chain is structured around two primary dimensions: chemical form and end-use application. Understanding how these segments interact is essential for identifying margin opportunities, forecasting capacity requirements, and aligning product roadmaps.
From a chemical form perspective, the market is divided between anhydrous barium bromide and barium bromide dihydrate. The anhydrous variant commands the larger share, driven by its stability profile and suitability for high-purity industrial and laboratory applications. The dihydrate form, while smaller in aggregate value, maintains steady relevance in specific downstream processes where hydrated chemistry is preferred or where supply chain logistics favor its handling characteristics. Our report dissects the pricing differentials, purity thresholds, and application suitability between these two forms, providing buyers and suppliers with a clear framework for product positioning.
On the application side, demand is anchored by several high-value use cases. Scintillator crystal production represents a major consumption node, leveraging barium bromide's optical and radiation-detection properties in specialized imaging and scientific instrumentation. Chemical synthesis and reagents constitute another substantial demand pillar, with BaBr2 serving as a precursor or intermediate in fine chemical pathways. Optical glass manufacturing absorbs a meaningful portion of supply, particularly where refractive index control and thermal stability are critical. A smaller but niche segment relates to specialty imaging and photography, where refined chemical grades support historically persistent demand in precision media applications.
Importantly, the relative weight of each application and region is not static. Regulatory shifts, feedstock pricing, and technological substitution can quickly reshape demand allocations. The report provides forward-looking segmentation scenarios that map how these drivers may redistribute market value across the forecast period, without relying on oversimplified proportional assumptions.
Supply-Side Dynamics and Raw Material Exposure
Barium bromide is predominantly produced by reacting barium carbonate or barium sulfide with hydrobromic acid. This fundamental synthesis route means that BaBr2 pricing and availability are tightly coupled to the cost structure of barium feedstocks and acid inputs. Recent industry data underscore this sensitivity: in the second quarter of 2025, barium carbonate prices in Italy climbed to approximately 678 USD per metric ton, propelled by rising barite and sodium carbonate costs alongside elevated energy and freight expenditures. Moving into the third quarter of 2025, UK barium carbonate pricing reached roughly 687 USD per metric ton, supported by stable demand from glass, ceramics, and chemical processing but pressured by higher energy tariffs and freight costs.
These feedstock trends are not isolated regional anecdotes. They reflect a broader pattern in which energy intensity, logistics congestion, and upstream mineral availability converge to influence downstream specialty chemical economics. Our BaBr2 Market Research report integrates these supply-side variables into a cohesive pricing and margin framework, helping procurement and finance teams anticipate cost volatility, negotiate contracts with informed benchmarks, and evaluate supplier diversification strategies.
Regulatory Landscape and Compliance Risk
Market participants must also navigate a shifting regulatory environment. Barium bromide is classified under transport regulations as UN1564, Barium compound, n.o.s., Hazard Class 6.1, Packing Group III, with corresponding documentation, labeling, and handling requirements that affect warehousing, shipping, and cross-border trade. In parallel, the substance is listed under EU REACH restrictions and appears in marine environmental policy frameworks as a hazardous substance, as reflected in ECHA listings. These designations influence import/export feasibility, customer qualification timelines, and the cost of compliance documentation.
For multinational operators, regulatory exposure is not uniform across geographies. The report maps jurisdictional nuances, identifies coverage gaps, and provides guidance on aligning sourcing and distribution strategies with evolving compliance expectations. This dimension is particularly valuable for organizations expanding into Europe or managing supply chains that traverse multiple regulatory regimes.
Competitive Landscape and Strategic Positioning
The BaBr2 market exhibits meaningful concentration, but also a diverse set of participants spanning commodity-scale producers, specialty-grade suppliers, and laboratory-focused distributors. Our analysis indicates that the top three firms command a combined share of approximately 42.5 percent, while the top five collectively represent around 58.8 percent of market value. This concentration pattern suggests that scale, distribution reach, and certification capabilities confer competitive advantage, but also leaves room for differentiated niche players who serve high-purity, high-compliance, or region-specific demand.
Among the entities profiled in the report, several stand out for their positioning and operational profile:
- AB Enterprises , headquartered in Mumbai, supplies and exports high-purity Barium Bromide across a broad application set spanning pharmaceuticals, textiles, plastics, dyes, food coloring, paints, and chemical refineries, with an emphasis on meeting international standards through superior purity chemicals.
- Vizag Chemical , based in Visakhapatnam, operates as a manufacturer, supplier, and distributor of industrial-grade Barium Bromide at 99 percent purity or higher, supported by ISO 9001:2015 certification, serving diverse industries within India and export markets.
- Axiom Chemicals Pvt Ltd , located in Vadodara, Gujarat, manufactures and exports both Barium Bromide Anhydrous and Dihydrate, aligned to CAS 10553-31-8 and 7791-28-8, targeting industrial chemical applications.
- Powder Pack Chem , also operating from Mumbai, offers Barium Bromide in powder form with 98 percent purity at LR grade, catering to laboratory and industrial use cases that prioritize accessible specifications.
- Sincere Chemical , a China-based producer, integrates R&D, production, and sales for Barium Bromide (CAS 10553-31-8), offering factory pricing and sample availability to support downstream evaluation and scaling.
- Stanford Advanced Materials (SAM) , in the United States, supplies high-quality BaBr2 at 99 percent purity in white bead form, positioned for advanced materials and chemical synthesis applications where form factor and purity consistency matter.
- Sigma-Aldrich (Merck KGaA) , with presence across the United States and Germany, provides anhydrous Barium Bromide beads in -10 mesh at 99.999 percent trace metals basis, targeting laboratory, research, and high-purity applications that require stringent material certification.
While recent public developments among these companies are not extensively highlighted in the current reporting cycle, the structural signals are clear: pricing power tends to accrue to suppliers with certified high-purity grades, reliable logistics, and credible compliance credentials. Conversely, buyers benefit from supplier diversification, total-cost-of-ownership modeling, and early alignment on purity and packaging requirements. The report's competitive intelligence section goes beyond company descriptions to evaluate relative positioning, supply reliability indicators, and the strategic implications of concentration for negotiation leverage and risk distribution.
Operational Content and Decision Support
Beyond macro trends and company profiles, the BaBr2 Market Research report is structured as a practical decision-support toolkit. It delivers actionable content across multiple analytical dimensions, enabling users to translate market intelligence into operational plans.
Key components include:
BaBr2 Market
- Supply-demand balance analysis that disaggregates production, consumption, and inventory dynamics to identify periods of tightness or slack, as well as the structural factors likely to drive future imbalances.
- Price trajectory modeling that correlates feedstock movements, energy inputs, freight costs, and demand elasticity to produce forward-looking price scenarios rather than single-point estimates.
- Regulatory and compliance mapping that clarifies classification, transport, and environmental restrictions relevant to sourcing, storage, and international shipment.
- Purity and grade benchmarking that compares specifications across suppliers and application types, helping technical and procurement teams match material requirements with cost-effective sourcing options.
- Competitive benchmarking that positions major players by scale, certification, geographic reach, and product form, supporting supplier selection and market entry evaluations.
- Scenario planning modules that test how shifts in regional demand, raw material availability, and regulatory actions could alter market outcomes across the 2026-2032 horizon.
This operational depth is designed for cross-functional use. R&D teams can align material specifications with realistic availability and pricing. Procurement can structure contracts around informed cost benchmarks and supplier risk profiles. Strategy and finance can incorporate segment and scenario insights into investment appraisals, capacity planning, and market entry assessments.
Why This Report Matters for 2026 Decision-Making
Entering 2026, organizations operating in or adjacent to the BaBr2 market face a convergence of incremental growth, feedstock volatility, and regulatory complexity. The headline CAGR of 4.3 percent provides a useful directional signal, but the strategic opportunities and risks are distributed unevenly across forms, applications, and geographies. Companies that rely solely on broad market averages risk misjudging regional demand intensity, underestimating compliance costs, or overpaying for specifications that exceed actual application requirements.
PW Consulting's BaBr2 Market Research addresses these blind spots by combining verified historical data, forward-looking modeling, and grounded supply-side analysis. The report does not simply recount what has happened; it provides the analytical scaffolding required to evaluate what should happen next. For buyers, that means better contract timing, more accurate budget planning, and stronger supplier negotiation positions. For suppliers, it means clearer product roadmaps, targeted certification investments, and more precise capacity allocation. For investors and strategic planners, it means a defensible basis for scenario analysis and risk assessment.
Accessing Full Intelligence
The insights summarized here reflect the report's analytical framework and directional findings, but the full intelligence payload extends well beyond this overview. Detailed segmentation analyses, granular demand and pricing scenarios, supplier benchmarking matrices, and regulatory coverage maps are structured to support immediate operational use. Because market conditions and input costs can shift rapidly, decision-makers benefit from accessing the complete dataset and scenario tools directly.
To obtain the full BaBr2 Market Research report and integrate its comprehensive data, models, and strategic guidance into your 2026 planning cycle, visit the source page for complete access and detailed methodology.
Lithium Bromide Market
For detailed analysis of this topic, please visit the official page: BaBr2 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Robot Precision Reduction Gears Market to Grow at 11.01% CAGR$9.78B by 2032
By pmarketresearch, 2026-09-16
Navigating the Future of Motion Control: Strategic Insights from the Worldwide Industry Robot Precision Reduction Gears Market Analysis
In the rapidly evolving landscape of industrial automation, precision is not merely a specification; it is the cornerstone of competitive advantage. As enterprises across the globe accelerate their adoption of robotics, the demand for high-performance motion control components has surged. PW Consulting is proud to present our latest comprehensive study on the Worldwide Industry Robot Precision Reduction Gears Market. This report is designed to serve as a critical strategic asset for decision-makers navigating the complexities of the 2026 business environment and beyond.
The precision reduction gear is the unsung hero of robotic motion. Responsible for translating high-speed motor rotations into precise, high-torque movements with minimal backlash, these components are vital for applications ranging from delicate assembly tasks to heavy-industry welding. Understanding the market dynamics surrounding this niche yet pivotal sector is essential for stakeholders looking to secure supply chains, invest in R&D, or capture market share. Our analysis provides a granular view of where the industry stands today and where it is headed through 2032.
Market Trajectory and Growth Dynamics
The economic indicators surrounding the robot precision reduction gears market depict a robust trajectory of expansion. Based on our analysis, the global market revenue stood at USD 4710.0 Million in 2025, reflecting a steady upward curve from USD 2850.4 Million in 2020. This historical growth underscores the increasing integration of automation in manufacturing processes worldwide. Looking forward, the market is projected to reach USD 5051.76 Million in 2026, marking a significant milestone in the forecast period ranging from 2026 to 2032.
The Compound Annual Growth Rate (CAGR) for the forecast period is estimated at 11.01%. This sustained growth rate signals more than just a temporary boom; it indicates a structural shift in industrial capabilities. By 2032, the market is anticipated to expand substantially, driven by continuous innovation in robot design and the widening scope of automated applications. For enterprise strategists, these figures highlight the urgency of aligning investment portfolios with the scaling demands of the precision gear sector. The momentum suggests that companies capable of navigating supply chain complexities and technological requirements will find ample opportunity for revenue generation in the coming years.
Key Market Drivers and Industry Dynamics
Several converging factors are propelling the demand for precision reduction gears. Firstly, the broader industrial robot production sector saw a strong rebound in 2025, with Asia leading the recovery. This resurgence has directly influenced the precision geared products market, which recorded growth in 2025 and is projected for a further rise in 2026. This expansion is supported by manufacturing sector recovery and emerging demands, including those from the humanoid robot sector. As robots become more pervasive in collaborative environments, the requirements for safety, smoothness, and precision intensify, directly impacting gear specifications.
Secondly, the technical imperatives of Industry 4.0 are reshaping product requirements. Modern smart factory automation demands higher precision and reliability. Consequently, precision gearboxes for robotics now emphasize zero backlash, high torque density, and compact design. Manufacturers are increasingly tasked with delivering components that can withstand high-speed operations while maintaining rigidity. These performance criteria are not static; they evolve as robot applications become more sophisticated, requiring gear manufacturers to innovate continuously to remain viable.
Raw Material Market Influence
Strategic planning in this sector cannot occur in a vacuum; it must account for upstream material costs. Alloy steel, a primary raw material for precision reduction gears, is critical due to requirements for high strength, rigidity, and durability. Market estimates suggest the alloy steel market holds significant value in 2026 with projected expansion through 2033. The cost stability and availability of such materials are paramount for gear manufacturers to maintain margin integrity.
Furthermore, global steel pricing dynamics play a crucial role in production costs. As of early 2026, world steel prices are observed to be at or near the bottom of the current cycle. With little meaningful global recovery expected in the same year due to overcapacity and weak demand factors, manufacturers may experience a temporary relief in input costs. However, strategic planners must remain vigilant. Understanding the correlation between raw material cycles and production scheduling is essential for optimizing procurement strategies and maintaining competitive pricing in the downstream robotics market.
Diverse Applications and Technological Types
The market for robot precision reduction gears is not monolithic. It is segmented by various technological types and application scenarios, each with distinct performance requirements and growth drivers. Understanding the composition of these segments allows enterprises to target their solutions more effectively.
Worldwide Industry Robot Precision Reduction Gears Market
Technologically, the market is defined by several key gear types. These include RV Reducers, which are known for their high torque capacity and durability, making them suitable for heavier robotic joints. Harmonic Reducers represent another significant category, prized for their zero-backlash characteristics and high precision in compact spaces. Planetary Reducers also occupy a niche, often utilized in applications requiring specific dynamic properties. Each type offers a trade-off between torque, precision, size, and cost, necessitating a detailed understanding of application needs to select the appropriate technology.
On the application side, the demand is distributed across various robot architectures. Articulated Robots continue to be a major driver, given their versatility in welding, painting, and material handling. Collaborative Robots, designed to work safely alongside humans, are gaining traction due to their flexibility and ease of deployment, requiring gears that ensure smooth and safe motion. SCARA Robots and Delta Robots also contribute to market demand, each requiring specialized gear solutions to maximize their respective strengths in high-speed pick-and-place operations and specialized assembly tasks. The interplay between these application types and gear technologies defines the market structure and influences procurement strategies for robot integrators.
Competitive Landscape and Key Players
The competitive environment within the robot precision reduction gears market is characterized by a high degree of concentration. Navigating this landscape requires a clear understanding of the key players who dominate supply and drive innovation. Our analysis indicates a market where a few major entities hold significant influence over pricing, technology standards, and availability.
Market concentration is substantial, with the top three companies holding a considerable percentage of the market share, and the top five entities commanding an even larger portion of total revenue. This concentration suggests that supply chain resilience is closely tied to the operational health of these key manufacturers. For enterprises relying on these components, diversifying suppliers or securing long-term contracts with these leaders may be necessary to mitigate risk.
Strategic Focus of Leading Manufacturers
Several key companies define the current competitive arena. Nabtesco Corporation, headquartered in Tokyo, Japan, stands as a world-leading manufacturer, particularly in precision reduction gears for industrial robot joints. Their focus on high torque, rigidity, and low backlash offerings positions them strongly in the medium-to-large robot segment. Recent developments highlight their strategic push; in early 2026, Nabtesco Precision Europe overhauled its product and service range with an emphasis on precision gears and mechatronic systems. Additionally, earlier showcases included new short gearbox technology with substantial power boosts, demonstrating a commitment to compact design and efficiency.
The Harmonic Drive family of companies, with entities in the USA, Germany, and Japan, remains a pioneer in strain wave precision reduction gears. Their solutions are critical for applications demanding high precision and compact size. Similarly, Sumitomo Drive Technologies in Japan manufactures high-precision cycloidal reducers, emphasizing zero backlash and long lifetime for high-speed drives. These Japanese manufacturers collectively set a high bar for performance standards in the industry.
Robot Joint Precision Reducers Market
European participation is also notable. SPINEA, based in Slovakia, operates as a key European manufacturer of precise cycloidal and harmonic solutions, supplying directly to leading robot manufacturers. German firms like Neugart GmbH and WITTENSTEIN SE offer specialized precision planetary gearboxes optimized for delta and parallel robots, focusing on high dynamics and reliability. The presence of these European players adds a layer of regional supply security for clients operating within the continent.
In the Asia-Pacific region beyond Japan, companies like Leaderdrive in China specialize in strain wave reducers with significant production capacity and patents. Meanwhile, Nidec Drive Technology Corporation and Nidec-Shimpo in Japan provide high-precision gear reducers and motor technologies tailored for high-performance applications. Recent manufacturing support developments, such as new hobbing machines launched to support automation in gear production, indicate an upstream focus on improving manufacturing efficiency.
North American companies also play a role, with entities like Cone Drive and GAM Enterprises supplying a range of robotic gearboxes including strain wave, cycloidal, and zero-backlash planetary types. This global spread of manufacturers underscores the international nature of the supply chain, though the concentration indices suggest that dominance remains weighted towards specific regions and established players.
Strategic Outlook for 2026 and Beyond
As we move through 2026, the strategic implications of these market dynamics are clear. For manufacturers, the focus must remain on technological differentiation. With market growth projected at a double-digit CAGR, competition for market share will intensify. Innovations that reduce size while increasing torque, or that improve efficiency and reduce lifecycle costs, will be key differentiators.
For robot integrators and end-users, supply chain stability is a primary concern. Given the high market concentration, reliance on a single source of precision gears could pose risks. Developing robust supplier relationships and understanding the capacity constraints of key players is essential. Additionally, keeping abreast of raw material trends, such as steel pricing cycles, can inform timing for capital expenditures and inventory management.
The emergence of new application areas, such as humanoid robots, adds another layer of opportunity. As these new forms of robotics mature, they will likely demand specialized gear solutions that differ from traditional industrial arms. Companies that can adapt their R&D pipelines to these emerging needs will be well-positioned to capture early-mover advantages.
Acquiring Comprehensive Intelligence
While this overview provides a high-level perspective on growth trajectories, competitive dynamics, and industry drivers, the full depth of the market requires detailed examination. Strategic decisions regarding market entry, capacity expansion, or partnership formation demand precise data that goes beyond general trends.
Our full Worldwide Industry Robot Precision Reduction Gears Market research report offers an extensive breakdown of segmentation data, historical performance, and detailed forecasts across all major regions and application types. It includes in-depth profiles of key competitors, an analysis of regulatory environments, and a detailed assessment of supply chain vulnerabilities. For stakeholders seeking to transform market intelligence into actionable strategy, accessing the complete dataset is invaluable.
To leverage the full potential of this analysis for your organization, we invite you to explore the complete report. Detailed segmentation splits, regional revenue specifics, and granular competitive benchmarking are available to subscribers. Equip your leadership team with the precise intelligence needed to navigate the complexities of the precision gears market in 2026 and secure a competitive edge in the automation sector.
For detailed analysis of this topic, please visit the official page: Worldwide Industry Robot Precision Reduction Gears Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com